“Traded 10 Billion Won With 100 Million Won, Then ‘-40 Million Won’ Showed Up”... The Fate of a Woman in Her 60s Who Day-Traded After Cashing In Her Husband’s Life Insurance
- Input
- 2026-11-14 05:00:00
- Updated
- 2026-11-14 05:00:07
[Financial News] Older investors aged 60 and over and women investors have drawn attention for posting higher average returns than younger investors in securities industry statistics. But a report on the dangerous practices of so-called “twilight ants”—older retail investors whose retirement assets are at risk because they have fallen into excessive short-term trading—has sounded the alarm. One investor started with 120 million won and racked up a cumulative trading volume of a staggering 10 billion won over three years, but frequent trading fees and averaging down in a falling market wiped out a third of her principal and left her household facing a liquidity crisis.
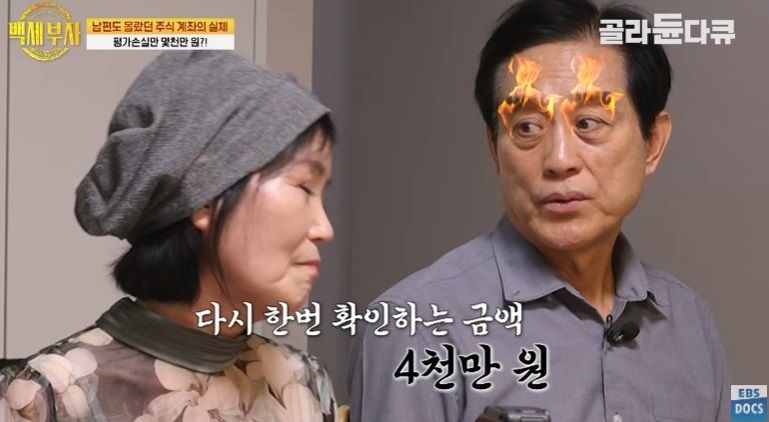
The EBS educational program “Baekse Buja: A Retirement Battle Between a Stock-Trading Wife and a Worker-Ant Husband,” which aired on the 9th, featured a sharp disagreement over financial management between Kim Hong-gi (70), who retired from the civil service and now works as an apartment building manager, conscientiously embarking on “the second chapter of his life,” and his wife, Park Eun-hui (65), who has invested in stocks for 30 years and spends every morning focused on day trading.
120 Million Won in Principal, 10 Billion Won in Cumulative Trades... Averaging Down After Cashing In Even Her Husband’s Insurance
According to the program, Ms. Park began trading stocks as a pastime she could pursue at home after suffering a serious illness in the past. Every morning, after hiking, she sits in front of her smartphone and computer as soon as the market opens and buys and sells stocks. She has repeatedly used the classic day-trading and averaging-down strategies: selling immediately when prices rise, and buying more when they fall. “I mostly day-trade. I get bored, so it’s kind of like a money game,” Ms. Park said. “On days when I make a lot, I can make 6 million won, and when I lose, I lose about 6 million won.”
Ms. Park invested about 120 million won in principal, but the cumulative value of trades that passed through her account over the past three years reached about 10 billion won. Her husband, Mr. Kim, who learned this only later, was stunned. “How does it make sense to trade 10 billion won with 100 million won?” he said. Despite the impressive trading volume, the account showed a devastating unrealized loss of about 40 million won, equivalent to a return of roughly -30% to -40%.
Even more seriously, she had cashed in insurance—one of their safeguards for retirement—to raise money for additional purchases in a falling market. Ms. Park revealed that she had canceled the policies and put the money into her stock account, shocking her husband. “There were life and cancer insurance policies in my husband’s name. We paid 150,000 won a month for 20 years, about 30 million won in total, but when I checked the surrender value, it was only 16 million won,” she said. An investment that began with a mother’s wish to leave even one building to her son ended up eating into the assets meant to secure their retirement.
Monthly Income of 7.1 Million Won, Yet 100 Million Won Short on the Jeonse Deposit... The Boomerang Effect of Managing Assets Separately
To make matters worse, the couple had been secretly managing their assets separately, bringing their looming real estate liquidity crisis to the surface. Their combined monthly fixed income is a solid 7.1 million won, made up of Mr. Kim’s civil service pension of 3.5 million won and his salary as an apartment building manager of 3.6 million won. But trouble began when, two years ago, they rented out their apartment in Seoul’s Dongdaemun District on a jeonse basis, bought an apartment in Yangju City, Gyeonggi Province, and moved there. They must return the tenant’s jeonse deposit of 460 million won when they move back into their Seoul home next March. But the market value of their current apartment in Yangju has fallen to around 350 million to 360 million won, leaving them about 100 million won short in cash.
Mr. Kim argued that his wife should sell the stocks she owns, even at a loss, and use the proceeds toward returning the jeonse deposit. Ms. Park pushed back, saying, “All the money we’ve saved so far will disappear,” and insisted she could not sell the stocks until she had recovered her principal, leading to a tense standoff.
The Flip Side of Older Investors’ Top Average Returns... “Day Trading Is a Casino, Not Investing”
The blind spot for individual investors stands in contrast to recent return statistics for older investors released by securities firms. Mirae Asset Securities analyzed returns for customers with account balances of at least 1 million won from January through May this year. Men aged 70 and over (42.1%), women aged 70 and over (41.69%), and women in their 60s (39.36%) ranked at the top. An analysis by NH Investment & Securities of roughly 2.24 million active accounts from January through September last year also found that women aged 60 and over ranked first, with returns of 26.9%. But these figures are averages that reflect a tendency to hold blue-chip stocks for the long term. Analysts say that investors who, like Ms. Park, engage in high-frequency turnover trading are inevitably exposed to enormous transaction costs and volatility.
John Lee, the former CEO of Meritz Asset Management and now head of “John Lee’s Rich School,” offered advice on the program that day. After analyzing Ms. Park’s trading history, he pointed out, “The trading fees and taxes alone paid to securities firms for trading 10 billion won over three years would amount to 20 million to 30 million won.” He added that “a considerable portion of the 40 million won unrealized loss came from the costs of frequent trading.” He issued a strong warning: “Stock investing is about letting companies work, rather than working myself, and sharing in the fruits. Buying and selling every morning in an attempt to predict price movements isn’t investing; it’s like going to a casino, and you’re bound to fail 100% of the time.”
“Financial Knowledge, Not a Building, for Her Son... Better to Cut Losses Than Borrow”
Mr. Lee stressed that to prepare for retirement, investors should stop pursuing short-term gains and shift to long-term investing, holding stakes in sound companies for a long time through tax-advantaged accounts such as pension savings funds. He also advised parents to pass on sound financial knowledge to their children instead of fixating on buying them a building.
On the urgent issue of returning the jeonse deposit next March, he said, “It’s wrong to cling to stocks no matter what just because you’ve taken a loss. It’s much better to cut some losses than to borrow money and pay interest.” He also proposed practical ways to restructure their assets and restore housing stability while minimizing debt: selling the Yangju apartment, liquidating some of their stocks, and covering the shortfall through options such as a lump-sum withdrawal under the housing pension scheme.
[email protected] Moon Young-jin Reporter