[Financial News Editorial] Strike a Balance to Avoid ‘Government Control’ Misconceptions in Stabilizing the Capital Market
- Input
- 2026-11-13 14:37:41
- Updated
- 2026-11-13 14:37:41
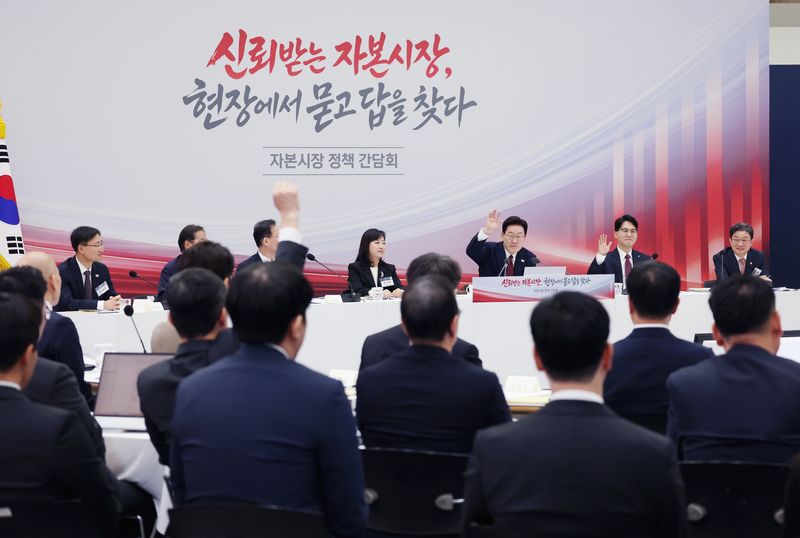
[Financial News] President Lee Jae Myung visited the Korea Exchange in Yeouido on the 13th, held a meeting on capital market policy and said, “Normalizing the capital market is a firm policy direction of the government.” His visit to the market in person to express his commitment to reform at a time when stock indexes are undergoing a sharp correction can be seen as lending support to market stability. Lee said he had separately instructed the Serious Crimes Investigation Agency (SCIA) to crack down strictly on unfair practices in financial markets, declaring his determination to boost market confidence. Even so, the stronger the government’s commitment to cleaning up the market, the more it needs to consider whether market autonomy may be curtailed.
The same applies to the measures announced earlier to improve governance at financial holding companies. The government and ruling party have proposed making the committee that recommends candidates for CEO positions at financial holding companies consist entirely of independent directors, and raising the approval threshold for reappointment above that required for a special resolution under the Commercial Act. The proposal also included expanding the channels through which pension funds, including the National Pension Service, can recommend outside directors. While the goal of reforming the “self-reappointment” structure is understandable, successive government measures affecting financial markets are fueling market concerns about the possibility of government-directed finance.
The government must also proceed with the utmost caution, as its determination to normalize the market could inadvertently distort the market itself. Indeed, when discussing the mandatory tender offer system that day, President Lee himself said, “Minority shareholders should be given a fair opportunity, but this could inadvertently become an obstacle to mergers and acquisitions (M&A).” His remarks took this concern into account. Capital markets involve complex product structures and a range of stakeholders with competing interests, so the effects of regulations must be carefully assessed before they are introduced. Designing policies to minimize unintended consequences is as important as the good intentions behind them.
Financial markets are open to the world and therefore sensitive to confidence. In markets with a high share of foreign investment, as in Korea, predictability in the process of making and enforcing regulations is paramount, just as much as the substance of the regulations. Regulation itself is not the problem; global investors will trade with confidence only when regulatory procedures and transparency are assured. If the perception spreads that government intervention is excessive, regardless of the government’s good intentions, the “Korea discount” will deepen.
With KOSPI share prices seesawing sharply in recent times, the government is likely to grow increasingly anxious about stabilizing the market. It is likely to want to take decisive action and intervene to promote market stability. The more so, the more clearly the government must draw the line between market normalization and market intervention. To that end, when introducing major market regulations, the government needs to communicate fully with market participants and adjust the pace. If standards change without adequate advance notice and public discussion, investors acting in good faith could be harmed. This is a time when the government needs a sense of balance to ensure that its determination to normalize the market is not misconstrued as market intervention.