[Editorial] Securities firms must stop issuing stock forecasts with an “if it doesn’t pan out, so what?” attitude
- Input
- 2026-11-10 18:33:38
- Updated
- 2026-11-10 18:33:38
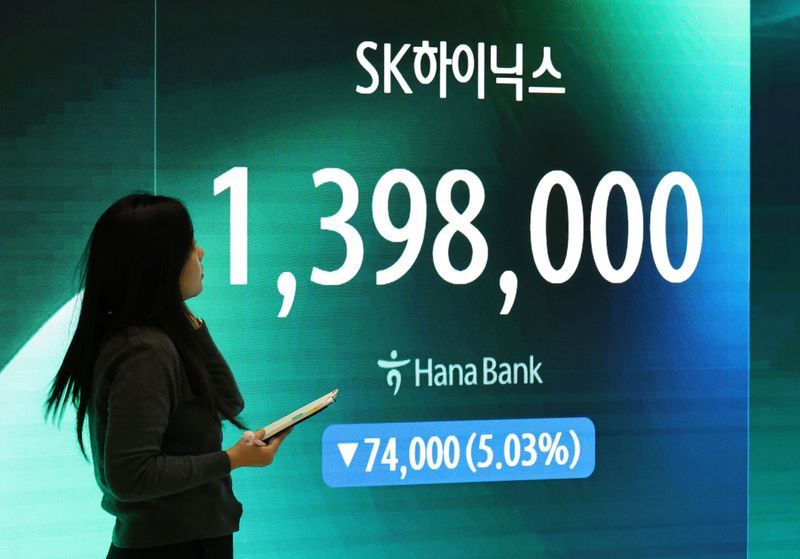
In early July, KB Securities put the upper end of its KOSPI forecast for this year at 12,000, but after stock prices fell, it recently revised its forecast range for next year to 5,100–9,000. The gap between the low and high ends is as much as 3,900 points. Daishin Securities and DB Securities, which in June had set their highest forecasts for this year at 11,500 and 11,700, respectively, also slashed them to 5,200–6,700 and 5,000–7,300. In just a few months, their forecasts were cut by at least 4,000 points.
Major stocks’ target prices are also being lowered. In a report issued on the 9th, Morgan Stanley cut its target price for SK hynix by about 38%, from 2.6 million won to 1.6 million won. It also lowered its target price for Samsung Electronics by about 19%, from 381,000 won to 309,000 won.
Any investors who bought stocks in the first half of the year trusting securities firms must have suffered heavy losses. The firms take no responsibility for this; all responsibility rests with the investors. These “if it doesn’t pan out, so what?” stock forecasts are actually harming individual investors, especially those without expertise in stocks who also have difficulty getting advice. Investors are furious at securities firms for belatedly lowering their forecasts only after stock prices have plunged.
There is a reason securities firms issue relentlessly optimistic forecasts. Brokerage firms, which earn revenue from commissions, make money by drawing investors into the market and keeping them there. They cannot take a clear-eyed look at reality and tell investors to stop trading stocks and take a break. In other words, they are luring investors with optimistic forecasts to make money.
The stocks recommended by securities firms are no different. They may recommend stocks after conducting their own analyses, but stock prices rarely move as the firms predict. Some firms even sell off a stock after recommending it. This also happens on stock-market broadcasts: they buy a stock, recommend it on air, and then sell their holdings if its price rises. There have even been cases in which people were actually punished for this.
Authorities need to establish standards and principles for securities firms’ recommendations and forecasts. If it is difficult to hold the firms legally responsible, one measure would be to require them to clearly disclose that their predictions may be wrong. Securities firms, too, should be extremely cautious when issuing forecasts and adopt a conservative approach.
Although confidence in South Korea’s stock market has reportedly improved, manipulation and fraud are still rampant. Many individual investors suffer heavy losses while seeking help from so-called “stock-tip chat rooms.” There are also countless cases of investors with nowhere else to turn trusting securities firms and impulsively investing, only to suffer losses. The firms’ responsibility is substantial. Investors who have suffered losses have nowhere to turn to complain. For investors’ sake, it would be better to stop issuing bogus forecasts and stock-price predictions.