“KRW stablecoins must be launched safely and quickly” ... Challenges after the Digital Asset Basic Act
- Input
- 2026-11-10 17:03:46
- Updated
- 2026-11-10 17:03:46
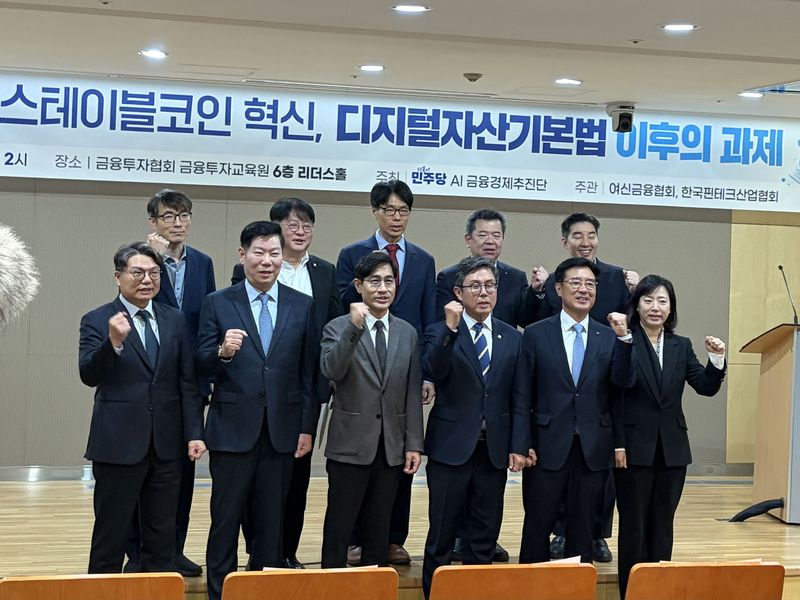
[Financial News] “What we need to do now is get started safely and quickly. Risk management and safeguards are essential. We need to put robust safeguards in place to prepare for risks that could arise from large-scale redemptions, sudden shifts in bank deposits, foreign exchange, and overseas circulation.”
Song Min-taek, an adjunct professor at Hanyang University’s Graduate School of Business, made the remarks at a seminar titled “Challenges After the Digital Asset Basic Act,” hosted on the 10th by the Democratic Party of Korea’s AI Financial Economy Promotion Group at the Korea Financial Investment Association’s Financial Investment Education Institute in Yeouido, Seoul.
Experts at the seminar said that policymakers should consider the potential for innovative finance as well as a bank-centered issuance structure, and should speed up market entry while putting safeguards in place, including measures to prevent money laundering.
“Bank-centered issuance is not the only solution”
In a presentation titled “Financial Innovation Based on Stablecoins and Domestic and International Cases,” Professor Song said, “We cannot ignore banks’ risk-management capabilities or their brand and credibility.” He added, “Careful judgment is needed on whether ‘50%+1’ can provide all the answers.” While acknowledging banks’ risk-management capabilities and credibility, he expressed skepticism about the “50%+1” model, under which banks hold more than half of the shares in a stablecoin-issuing consortium.
He went on to say, “We need to consider which matters more: the benefits of bank-centered participation or the benefits of innovative finance built around new business models,” adding, “We need an approach that allows us to get started quickly and safely.”
Professor Song also predicted that the longer institutionalization is delayed, the greater the opportunity costs that domestic companies and financial firms will face. “Transactions using dollar stablecoins are building up now, and it’s not just transactions that are accumulating; they’re also becoming connected to companies’ enterprise resource planning (ERP), accounting, and tax systems,” he said. “It won’t be easy to switch to won-denominated stablecoins later.”
“Responsibility for illicit fund flows must be clearly defined”
Participants at the seminar also said that regulatory gaps in the circulation stage after issuance must be addressed to make stablecoins commercially viable.
Jung Young-gi, an attorney at Kim & Chang, said in a presentation titled “Follow-up Tasks for Commercializing Stablecoins After the Digital Asset Basic Act,” “Regulatory discussions currently focus mainly on issuance and final redemption, but in practice the biggest issue is the scope of responsibility during circulation.”
Jung noted that stablecoins’ price stability, high liquidity, and ability to move across borders are advantages for financial innovation, but can also increase the risk of money laundering.
He proposed several legislative follow-up measures to support the commercial use of stablecoins: designating issuers as the parties responsible for anti-money-laundering obligations; codifying the requirements and procedures for freezing, blocking, and burning stablecoins; dividing responsibility among participants in the circulation stage; ensuring consistency with the Foreign Exchange Transactions Act; and establishing public-private information-sharing infrastructure and a risk-based regulatory framework.
Jung stressed, “It must be made clear how far the original issuer should be held responsible if a stablecoin is used in connection with illicit funds as it is transferred multiple times.” He added, “Businesses involved in circulation, such as exchanges and payment gateway (PG) providers, should share anti-money-laundering obligations according to their respective roles.”
Jung also said, “It is important to accurately assess risks and apply regulations suited to those risks,” adding, “Issuers’ anti-money-laundering capabilities should be assessed starting at the authorization stage, while the scope of responsibility in the circulation stage must also be clearly defined.”
[email protected] Seo Ji-yun Reporter