Japan and China routes expanded, costs cut ... Jeju Air’s target price raised 20%
- Input
- 2026-11-10 08:36:02
- Updated
- 2026-11-10 08:36:02
On the 10th, Park Soo-young, a researcher at Hanwha Investment & Securities, said, "Its flexible operations stand out among domestic airlines," adding that "this remains a favorable time to maintain a Buy stance."
Jeju Air posted results above market expectations in the third quarter, but earnings are expected to decline in the fourth quarter due to the off-season and rising jet fuel prices. However, with demand on its Japan and China routes remaining solid, the likelihood of returning to operating losses as in the past is considered limited.
Last month, the number of round-trip flights on Jeju Air's Japan routes rose 16% from the same period a year earlier, while the number on its China routes increased 57%. By contrast, the number of flights in the Asian region, including Southeast Asia, fell 10%. This resulted from reducing capacity in areas with weak demand and concentrating aircraft on routes attracting travelers.
Park said, "Flexible route operations are expected to align with strong demand centered on Japan and China, while cost savings through fleet standardization will enable flexible growth in revenue and earnings."
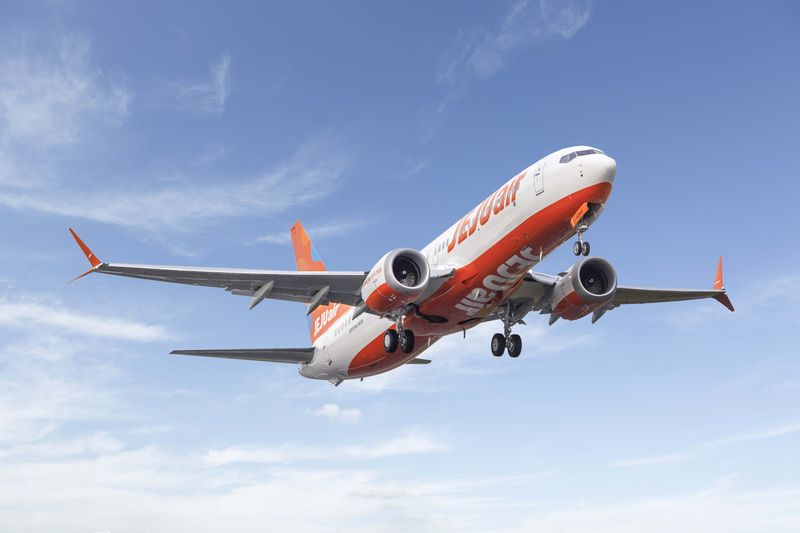
Cost savings from introducing new aircraft are also expected. Jeju Air is replacing Boeing 737-800 aircraft held under operating leases with purchased 737-8 aircraft. The resulting savings on lease payments, maintenance and fuel are estimated at about 14%. At the end of the third quarter this year, one-third of its total fleet consisted of newly purchased aircraft; that share is expected to reach 50% by the end of next year.
Jet fuel prices will be a key factor in next year's results. Hanwha Investment & Securities raised its jet fuel price forecast to an annual average of $131 per barrel, up from its previous estimate. Even so, it expects Jeju Air's operating profit next year to reach 144 billion won, up 51.6% from this year's forecast of 95 billion won.
Park emphasized the potential for improved results through cost savings and more efficient route operations, saying, "Depending on jet fuel prices, operating profit estimates have room to move higher." Compared with the closing price of 6,830 won on the 9th, the target price implies 31.8% upside.
[email protected] Bae Han-geul Reporter