LIG D&A target price cut in half on delayed orders and weak earnings... “Kolmar Korea’s share-price decline is a buying opportunity” [Stocktopia]
- Input
- 2026-11-09 10:54:51
- Updated
- 2026-11-09 10:54:51
[Financial News] Here is a roundup of reports from major securities firms on the morning of November 9.
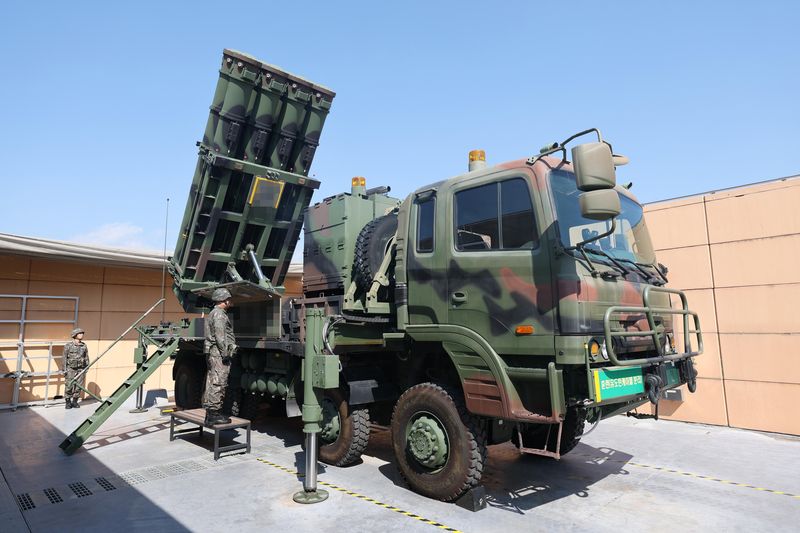
LIG Defense & Aerospace, a guided-weapons manufacturer, has seen its target price cut to around half its previous level as export orders have not come in as quickly as expected and third-quarter results fell short of market expectations.
Kolmar Korea’s third-quarter consolidated operating profit fell short of expectations, but its domestic business continued to grow steadily, leading analysts to view the recent share-price decline as a medium- to long-term buying opportunity. Analysts also expect Samyang Foods to maintain strong earnings momentum next year, with its European subsidiary joining the growth trajectory after its U.S. business.
LIG D&A: Concerns over weakening missile premium (Samsung Securities)
◆ LIG Defense & Aerospace (079550)— Samsung Securities / Analyst Han Young-soo- Target price: 430,000 won (down 49.7% from 855,000 won) | Previous close: 326,000 won
- Rating: Buy (maintained)
Samsung Securities cut its target price for LIG Defense & Aerospace to 430,000 won, saying the share-price premium attached to its guided-weapons business could weaken. Third-quarter operating profit was 68 billion won, 34.6% below market expectations.
Analyst Han Young-soo said, “The large-scale orders needed to meet market expectations, which have risen amid geopolitical conflicts, have yet to materialize.” He also cited uncertainty surrounding sanctions by the Defense Acquisition Program Administration as a risk factor.
However, Han said, “Even based on the lowered earnings outlook, the company’s current valuation remains discounted compared with the average for domestic and overseas peers.” Although near-term headwinds are substantial, analysts say the recent sharp share-price drop has already priced in a considerable portion of the bad news.
Kolmar Korea: Production-capacity concerns can be managed (SK Securities)
◆ Kolmar Korea (161890)— SK Securities / Analyst Hyeong Gwon-hun- Target price: 150,000 won (down 16.7% from 180,000 won) | Previous close: 108,900 won
- Rating: Buy (maintained)
SK Securities said Kolmar Korea’s third-quarter consolidated operating profit fell short of market expectations, but its domestic cosmetics original development manufacturing (ODM) business remained solid. It lowered its target price to 150,000 won to reflect the decline in share prices among peers. The domestic standalone entity posted its highest quarterly revenue on record in the third quarter, buoyed by a boom in K-beauty exports.
Analyst Hyeong Gwon-hun said, “Cosmetics ODM companies’ shares have been weak since September. We believe the market is pricing in uncertainty about next year’s business conditions more heavily than this year’s favorable conditions, as well as concerns about insufficient production capacity (CAPA) in the first half of next year.”
Hyeong expects that outsourcing production and using idle space at existing factory sites can buy time until the new Sejong plant is completed in the second half of next year. He added, “From a medium- to long-term perspective, the share-price decline is a buying opportunity.”※ Original Development Manufacturing (ODM)This is a model in which a manufacturer handles both product development and production, then supplies the products to brand owners. As exports by small and midsize cosmetics brands without their own factories grow, orders for ODM companies increase as well.
Samyang Foods: Shares look attractive relative to earnings (NH Investment & Securities)
◆ Samyang Foods (003230)— NH Investment & Securities / Analyst Ju Yeong-hun- Target price: 1,880,000 won (maintained) | Previous close: 1,220,000 won
- Rating: Buy (maintained)
NH Investment & Securities maintained its 1,880,000-won target price, saying Samyang Foods again set a quarterly revenue record in the third quarter despite unfavorable exchange-rate conditions.
Analyst Ju Yeong-hun said, “With its performance in the U.S. market continuing and its European subsidiary now entering a full-fledged growth trajectory, strong earnings momentum is expected to continue next year as well.”
The shares currently trade at around 13.6 times projected 2027 earnings. Analyst Ju said, “Given that the shares traded at an average PER of 20.9 times over the past three years, they are also attractive from a valuation perspective.” He added that the new plant in Jiaxing City, China, is expected to help meet rising demand and reduce costs when it begins operations next year.
[Stocktopia]is an AI-based stock report briefing that compiles and delivers reports from major securities firms in Korea. To keep receiving [Stocktopia], please subscribe on the reporter’s page.
[email protected] Seong Min-seo Reporter