Seven months after BDC's launch, just one product... “Securities firms' participation and other measures needed to spur growth”
- Input
- 2026-11-05 15:25:53
- Updated
- 2026-11-05 15:25:53
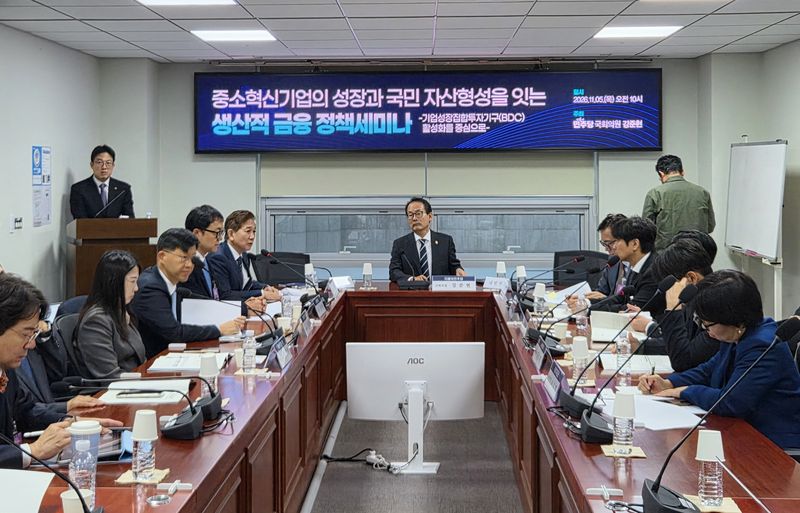
[Financial News] Seven months have passed since the Business Development Company (BDC) system took effect, but progress has been sluggish, with only one product launched. Calls are growing for institutional improvements to invigorate the BDC market, including allowing securities firms to participate and easing restrictions on lending and investment.
At the “Productive Finance Policy Seminar Linking the Growth of Small and Innovative Companies with the Building of Public Wealth,” held at the National Assembly Members' Office Building in Yeouido, Seoul, on the 5th, Kim Jin-young, a research fellow at the Korea Capital Market Institute,
stressed that securities firms' participation was important to expanding the BDC market. “When investing in unlisted companies, it is important to be able to identify sound companies with strong growth potential,” Kim said. “Securities firms have the capabilities to identify unlisted companies and assess their value through due diligence for initial public offerings (IPOs) and the setting of offering prices.”
A BDC is a publicly offered, listed fund that raises capital from investors and invests in unlisted venture and innovative companies, among others. At least 60% of its total assets must be invested in unlisted venture and innovative companies, as well as companies listed on KONEX and KOSDAQ.
The BDC system was introduced in South Korea last March. But in the roughly seven months since then, the only product to have entered the market is Shinhan Asset Management's “Shinhan Innovation Company Growth Investment Trust No. 1.”
Kim added, “For companies to move on to the next stage after receiving investment, relationship banking is also important: investors such as securities firms can help them obtain information and expand their networks.” He said, “For securities firms to properly support small and mid-sized companies, securities firms equipped with these capabilities need to participate as investors.”
Kim also argued that restrictions on loan investments should be eased in stages. Under the current system, BDCs must focus on stocks and equity-linked bonds, while loans are capped at 40%. In the United States, BDCs have established themselves as high-dividend products by adopting investment structures centered on loans.
Kim explained, “If a BDC is operated solely around equity investment, significant uncertainty around exits follows. Diversifying investment products into growth-oriented BDCs focused on equity investment and income-oriented BDCs focused on lending would allow people to invest in line with their preferred characteristics and risk appetites.”
Concerns were also raised that operating BDCs primarily around lending could weaken their original purpose of providing long-term risk capital to innovative companies. Kang Jae-won, a research fellow at the Korea Small Business Institute (KOSBI), said, “BDCs should serve as a long-term funding channel that frees companies from short-term repayment pressures and allows them to focus steadily on research and development and business expansion.” He added, “If income-oriented BDCs are introduced, it seems necessary to consider how they would be differentiated from existing lending products.”
[email protected] Seo Min-ji Reporter