Hyosung Heavy Industries target price cut from 4.3 million won to 3 million won; ‘Buy’ rating maintained — BNK Investment & Securities
- Input
- 2026-11-05 05:59:00
- Updated
- 2026-11-05 05:59:00
[Financial News] Analysts said Hyosung Heavy Industries’ results for the third quarter of this year came in below market expectations, prompting a cut in its target price from 4.3 million won to 3 million won. Delayed revenue recognition due to logistics disruptions and higher costs in the construction division were cited as the reasons for the weak results. However, the outlook for medium- to long-term earnings improvement was maintained, as the heavy-industry division’s order backlog had grown to 18.9 trillion won.
On the 5th, BNK Investment & Securities cut its target price for Hyosung Heavy Industries by 30.2%, from 4.3 million won to 3 million won. It maintained its ‘Buy’ rating. Lee Sang-hyun, an analyst at BNK Investment & Securities, said the firm had applied a conservative target price-to-earnings ratio (PER) to reflect uncertainty over U.S. trade and monetary policy and falling valuations among global peer companies.
Hyosung Heavy Industries’ consolidated revenue for the third quarter of this year was 1.7406 trillion won, up 7.2% from the same period a year earlier. Operating profit for the same period rose 10.8% to 243.5 billion won, but fell 20.6% short of the market estimate of 306.5 billion won. The operating margin was 14.0%, up 0.5 percentage points from a year earlier but down 1.7 percentage points from the previous quarter.
The main causes of the weak results were delayed revenue recognition due to logistics disruptions and higher costs in the construction division. Disruptions to maritime logistics caused by uncertainty in the Middle East and the impact of a typhoon in the United States pushed the recognition of revenue on about $100 million in high-margin heavy-industry shipments into the fourth quarter.
In the construction division, about 40 billion won in higher construction costs at some sites was reflected in the results. BNK Investment & Securities said the costs were one-off, reflecting the advance application of a conservative cost ratio, and that the possibility of further losses was limited.
However, order growth has continued. New orders in the heavy-industry division in the third quarter totaled 3.233 trillion won, up 122% from the same period a year earlier. The division’s order backlog grew 71% year over year to 18.899 trillion won. BNK Investment & Securities said this was the largest backlog on record. The U.S. market accounted for 68% of new orders and 60% of the heavy-industry division’s backlog.
BNK Investment & Securities estimated Hyosung Heavy Industries’ operating profit for the fourth quarter at 299 billion won, up 22.8% from the third quarter. It forecast improved results as heavy-industry revenue delayed by logistics disruptions is recognized in the fourth quarter.
For this year, it forecast revenue of 6.713 trillion won and operating profit of 959 billion won, up 12.5% and 28.4%, respectively, from the previous year. For next year, it projected revenue of 7.768 trillion won and operating profit of 1.206 trillion won.
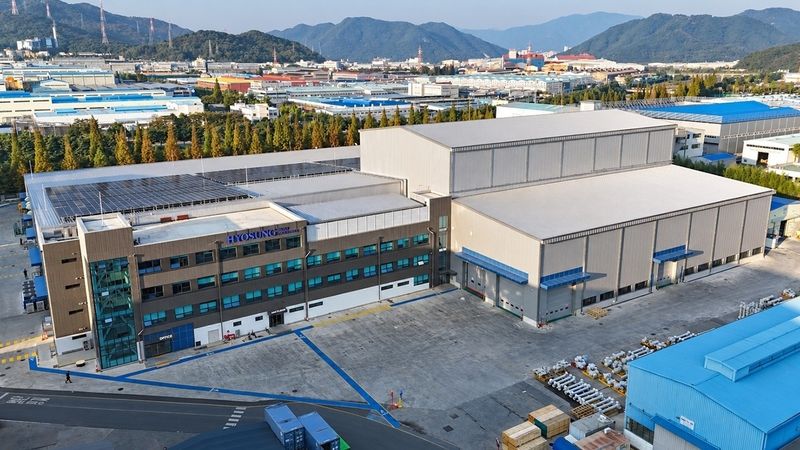
Expanded production capacity is also a factor in medium- to long-term results. Hyosung Heavy Industries plans to expand capacity at its Memphis plant in the United States from $300 million to $400 million through brownfield investment, and then to $700 million through greenfield investment. At its domestic Changwon plant, it has begun operating a new factory for export-bound ultra-high-voltage circuit breakers, built with an investment of about 100 billion won. Hyosung HICO Breaker, a joint venture established with U.S.-based Quanta Services, began mass production of ultra-high-voltage circuit breakers last October at its plant in Canonsburg, Pennsylvania.
The analyst forecast that “considering the heavy-industry division’s large order backlog, the expansion of high-margin business in the United States, and its competitive edge in high-voltage direct current (HVDC) technology, there is still room for medium- to long-term gains in the share price.”
[email protected] Kim Mi-hee Reporter