“KAI: It’s time to look at fighter jets, too” ... HYBE remains undervalued, trading near its IPO price despite record earnings [Stocktopia]
- Input
- 2026-11-04 11:18:18
- Updated
- 2026-11-04 11:18:18
[Financial News] Here is our roundup of reports from major securities firms on the morning of November 4.
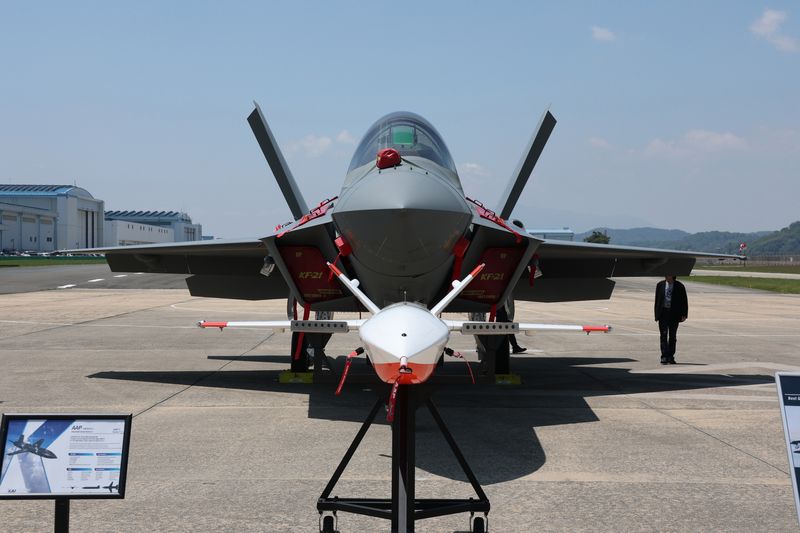
Analysts say KAI could see its corporate value re-rated as global fighter jet deliveries gather pace.
LG Energy Solution’s earnings estimate for next year was lowered, prompting a cut to its target price, but the company is still forecast to post record operating profit next year, buoyed by growth in Energy Storage Systems (ESS), among other factors. HYBE was described as undervalued, with its share price near its IPO price despite record results in the third quarter.
KAI: Now is the time to look at fighter jets (Hanwha Investment & Securities)
◆ KAI (047810)― Hanwha Investment & Securities / Researcher Chae Woon-saem- Target price: 150,000 won (up 7.1%, from 140,000 won) | Previous close: 97,300 won
- Investment rating: Buy (maintained)
Hanwha Investment & Securities said KAI’s third-quarter operating profit of 79.4 billion won met market expectations, supported by higher sales from mass-produced complete aircraft. The brokerage added that visibility on medium- to long-term earnings growth and expectations for new orders were increasing, and raised its target price to 150,000 won.
Researcher Chae Woon-saem said, “Now is the time to pay attention to fighter jet makers as well,” adding that “global fighter jet transaction volumes have been limited compared with those for ground weapons, but new orders have continued to accumulate.”
Chae said earnings growth at global fighter jet makers should gather pace if expanded production capacity leads to increased deliveries. He said KAI’s fighter jet deliveries were also “set to rise in steps from 2026.” The view is that KAI could be re-rated along with the broader global fighter jet industry if valuations across the sector rise.
Fourth-quarter operating profit is estimated at 167.1 billion won, exceeding consensus as mass-production volumes of complete aircraft for domestic and overseas markets are concentrated in the quarter. The brokerage expects it could raise its earnings estimates for 2027–2030 if KAI secures the Indonesian order it is targeting this year.
LG Energy Solution: Orders turn into earnings (Shinhan Investment & Securities)
◆ LG Energy Solution (373220)― Shinhan Investment & Securities / Senior Researcher Lee Jin-myeong- Target price: 460,000 won (down 8.0%, from 500,000 won) | Previous close: 338,000 won
- Investment rating: Buy (maintained)
Shinhan Investment & Securities cut its estimate for LG Energy Solution’s operating profit next year by 7%. It also lowered its target price to 460,000 won to reflect declining valuation multiples among competitors. However, it forecast operating profit of 3.81 trillion won next year, surpassing the 2.16 trillion won recorded in 2023 and setting a new record.
Third-quarter operating profit came to 756 billion won, above consensus of 326.4 billion won. Customer compensation payments, increased ESS shipments and an expansion of the Advanced Manufacturing Production Credit (AMPC) lifted earnings.
Senior Researcher Lee Jin-myeong forecast that next year, “operating profit excluding AMPC will also turn profitable, improving earnings quality.” North American ESS production capacity will rise from 50 GWh at the end of this year to 70 GWh at the end of next year. The explanation was that the 160 GWh order backlog already covers most of the volume for 2028.
The senior researcher focused on demand for battery energy storage systems (BESS) as AI data centers (AIDCs) expand, as well as local production capacity for lithium iron phosphate (LFP) batteries. He said, “As AIDCs expand, big tech firms are directly purchasing more BESS, while local LFP production capacity is an additional factor in winning orders.”※ Advanced Manufacturing Production Credit (AMPC)This is a tax credit provided to companies that produce battery cells, modules and other products in the United States, in proportion to their production volume. Korean battery makers include it in operating profit, so earnings excluding AMPC are used as an indicator of the underlying profitability of their businesses.※ Energy Storage System (ESS)An ESS stores generated electricity in batteries and supplies it when needed. In addition to helping balance output from renewable energy sources, ESSs are increasingly being used to stabilize power supply at AI data centers.※ Lithium iron phosphate (LFP)This is a battery that uses lithium, iron and phosphate in its cathode material. It has lower energy density than ternary batteries, but is cheaper and safer, so it is mainly used in ESSs.
HYBE: Top pick maintained despite undervaluation (Hana Securities)
◆ HYBE (352820)― Hana Securities / Researcher Lee Ki-hoon- Target price: 270,000 won (down 10.0%, from 300,000 won) | Previous close: 155,900 won
- Investment rating: Buy (maintained)
Hana Securities said HYBE’s valuation multiple continued to decline in a trend known as derating. It lowered its target price-to-earnings ratio (PER/P/E) to 29 times and cut its target price to 270,000 won, but continued to name HYBE its top pick.
HYBE’s third-quarter operating profit was 188.5 billion won, marking a return to profitability and beating consensus of 164.5 billion won. Researcher Lee Ki-hoon pointed to the impact of BTS’s world tour, saying, “Thanks to BTS’s historic world tour, HYBE posted record results that beat consensus in the third quarter, following the second quarter, despite the won’s strength.”
Even so, he noted that the current share price reflected “a 2027 forward P/E of only around 17 times, and is just 115% of the IPO price.”
Lee said the performance of major intellectual property (IP), including artists, is reflected in share prices in advance. He explained, “Share prices in the entertainment agency industry reflect the performance of major IP six months to a year ahead.” He said the share price had fallen despite strong results this year because BTS’s plans for next year were unclear. As a result, earnings next year were expected to decline by around 10% from this year, excluding about 250 billion won worth of shares gifted by the largest shareholder.
However, with plans for solo and group activities in the second half of next year mentioned in the latest earnings announcement, he forecast that “operating profit of around 500 billion won next year will be well within reach.” For 2028, he expects record annual operating profit of around 600 billion won, reflecting full-group activities by all 13 members of Seventeen and strong growth at CORTIS and KATSEYE.
[Stocktopia]It is an AI-powered stock report briefing that compiles and delivers reports from major domestic securities firms. Subscribe to the reporter’s page to keep receiving [Stocktopia].
[email protected] Seong Min-seo Reporter