Even the 1.4 million won level is under threat... “SK hynix to hit 3.2 million won. Now’s the time to buy”
- Input
- 2026-11-03 08:42:19
- Updated
- 2026-11-03 08:42:19
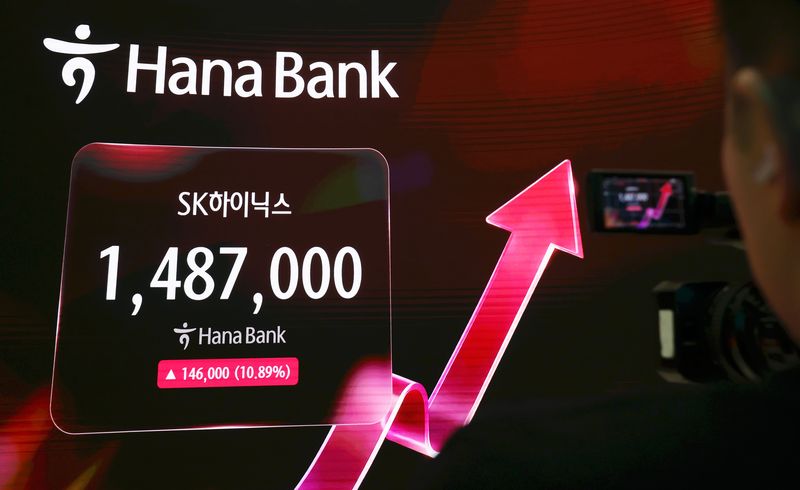
[Financial News] While the KOSPI continues to seesaw day after day, analysts say it is time to increase exposure to SK hynix. On the 3rd, Korea Investment & Securities set a target price of 3.2 million won for SK hynix and said an aggressive strategy of increasing its weighting remained valid. The reason, it said, is that market sentiment could shift sometime this month, and the current price appeal may be the last of its kind until year-end as next year’s first half approaches.
Ko Young-min, an analyst at Korea Investment & Securities, forecast that SK hynix’s fourth-quarter operating profit would rise 35% from the previous quarter to 112.1 trillion won, while revenue would increase 30% to 136.3 trillion won. He expected long-term supply agreements (LTAs) to account for 40% of shipments and revenue by the end of this year and around 50% next year. He also forecast that fourth-quarter DRAM prices would rise 18% from the previous quarter and NAND prices 13%.
Ko explained, “With supply far short of demand, this is a strategy to maximize the effect of buyers competing to bid prices up.” He added, “Selling prices for commodity memory are still rising steeply, and the companywide quarterly operating margin (OPM) has climbed to 82% and has yet to stop setting new highs.”
He forecast that next year operating profit would rise 73% year on year to 507.8 trillion won, while revenue would increase 66% to 619 trillion won. “It is significant that earnings are still well above our previous estimates even though we have lowered our exchange-rate assumptions substantially,” Ko said. “Ultimately, the key is the average selling price (ASP), and the trend of ASPs coming in higher than expected could continue on several more occasions next year.”
Ko identified commodity memory as a factor that could lift expectations in the first half of next year. “The rising selling prices of non-LTA products sold to server customers, which have driven the gains so far, will continue to stand out,” he stressed.
For the second half, he focused on high-bandwidth memory (HBM). Ko analyzed, “HBM contributed more than commodity memory to the third-quarter DRAM ASP coming in above our previous expectations.” He explained, “As the share of HBM4, the sixth-generation product, begins to rise in earnest from Q3 this year, the HBM ASP in Q3 appears to have surged to 29%, up 31 percentage points from -2% in the previous quarter.” He added, “Next year, the mix of HBM4E, the seventh-generation product, will increase and the pace of price rises will steepen; we expect that to happen between Q2 and Q3 next year.”
[email protected] Han Young-jun Reporter