Korea Capital Market Institute: Use of forward-looking disclosures continues to decline; policy improvements should be considered
- Input
- 2026-10-30 14:33:48
- Updated
- 2026-10-30 14:33:48
[Financial News] Concerns have been raised that use of the “forward-looking disclosure” system, through which listed companies publicly share forecasts of future business performance, including earnings, is in decline. One view is that policy measures, including improvements to the system centered on voluntary corporate participation, are needed to revitalize it.
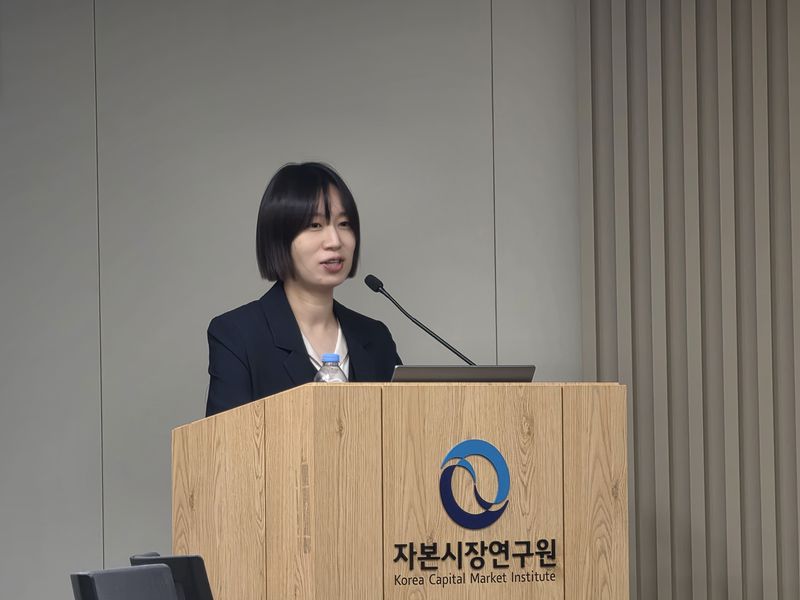
Lee Ha-yoon of the Korea Capital Market Institute gave a presentation on “The Status, Characteristics and Information Value of Forward-Looking Disclosures” at the Korea Financial Investment Association in Yeouido, Seoul, on the 30th.
Forward-looking disclosures rose rapidly through the mid-2000s, but have since shown an overall decline. According to the Korea Exchange’s KIND disclosure system, the number of forward-looking disclosures rose from 124 in 2002 to 269 in 2007, reaching its highest level. Since the 2010s, however, the figure has generally hovered around 100 per year. KOSDAQ disclosures also increased from 200 in 2004 to 325 in 2006, but have recently amounted to just 40 to 50 a year.
The researcher explained, “This decline may have been affected not only by the burden of managing and correcting disclosures after they are made, and by legal and institutional uncertainty surrounding forecast information, but also by changes in corporate characteristics such as industry composition, earnings volatility and predictability, and the share of loss-making companies.” The researcher added, “As companies have been able to use information channels such as investor relations (IR) presentations and conference calls, these may have replaced formal forward-looking disclosures.”
The study concludes, however, that forward-looking disclosures still convey meaningful information to the market. In fact, the market responded to the forecasts: share prices rose when companies’ projections exceeded existing expectations and fell when they came in below them.
The analysis also finds that corrective disclosures serve as a useful means of conveying information, not only by communicating newly obtained information to the market but also by prompting meaningful share-price reactions depending on the direction of the revision.
To revitalize the system, the researcher first stressed the need to improve predictability so companies can voluntarily provide reasonable information about the future. Under the current system, companies may receive a degree of exemption from liability if they prepare forecast information in good faith and meet key requirements. But because it is difficult for companies to determine in advance the scope of that exemption, the researcher said specific criteria for determining eligibility and examples of how they are applied should be provided.
The researcher also cited as policy considerations setting out companies’ substantive assumptions and the basis for their calculations in detail; establishing corrective disclosures as a normal part of the information-update process; expanding the use of reasonable forecast ranges; and pursuing improvements in information quality alongside these measures.
“With more widespread use of forward-looking disclosures, investors will be able to accurately assess companies’ future performance and uncertainties,” the researcher said. “The report’s central message is that we should create this kind of information environment.”
[email protected] Im Sang-hyeok Reporter