Hanwha Aerospace’s target price cut 43% on earnings volatility... “Already at ‘two strikes’”
- Input
- 2026-10-30 08:28:50
- Updated
- 2026-10-30 08:28:50
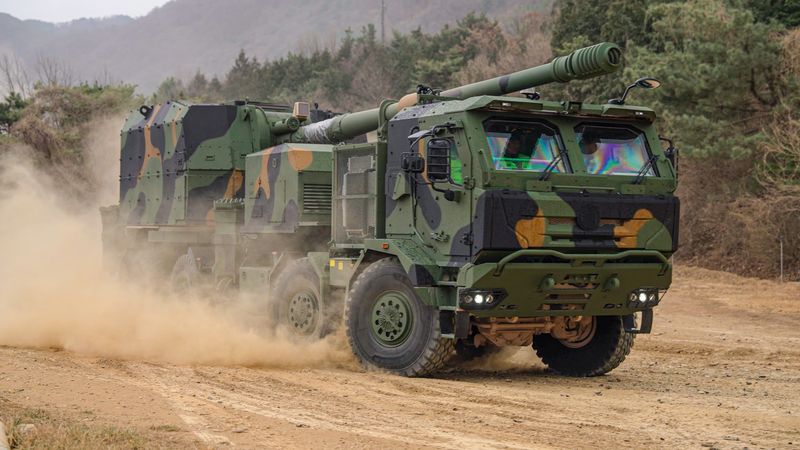
[Financial News] Daol Investment & Securities forecast that Hanwha Aerospace would recover in the fourth quarter on higher export volumes despite weak third-quarter earnings. However, reflecting earnings volatility and uncertainty over export profitability, it cut its target price by 43%, from 2.46 million won to 1.4 million won. It maintained its ‘Buy’ rating.
Daol Investment & Securities analyst Kwang-Sik Choi said on the 30th, “Hanwha Aerospace’s consolidated revenue in the third quarter was 6.0943 trillion won and operating profit was 452 billion won, down 6% and 46%, respectively, from a year earlier.” He added, “The fire at the Daejeon facility and bottlenecks in solid fuel are believed to have led to delayed exports and losses in the domestic business.”
In particular, the ground defense division’s revenue plunged 41% year over year to 1.2455 trillion won, while operating profit fell 96% to 21.7 billion won. The results were affected by one-off costs of 46 billion won resulting from the accident at the Daejeon facility, a decline in exchange rates, and export delays, among other factors. The share of exports in the ground defense division’s revenue also fell from 58% in the second quarter to 48% in the third.
However, earnings are expected to recover in the fourth quarter as deferred export volumes are recognized. Choi estimated fourth-quarter revenue and operating profit at 9.4791 trillion won and 1.3015 trillion won, respectively.
However, taking into account differences in profitability across export markets and volatility related to the timing of revenue recognition, the 2027–2028 operating profit forecasts for ground defense were cut by around 20%. The target price-to-earnings ratio (PER) was also lowered from 30 times to 20 times.
Choi said, “Since ground defense posted a loss in the first quarter of 2024, earnings have recovered sharply, and the order pipeline ahead is also strong, so I believe the stock is at a short-term bottom.” He added, “Two earnings shocks in three years feels like ‘two strikes.’”
[email protected] Im Sang-hyeok Reporter