LG Electronics Falls Short of Q3 Consensus, but It's Time to Focus on Growth in Its AI Cooling Business
- Input
- 2026-10-29 08:20:42
- Updated
- 2026-10-29 08:20:42
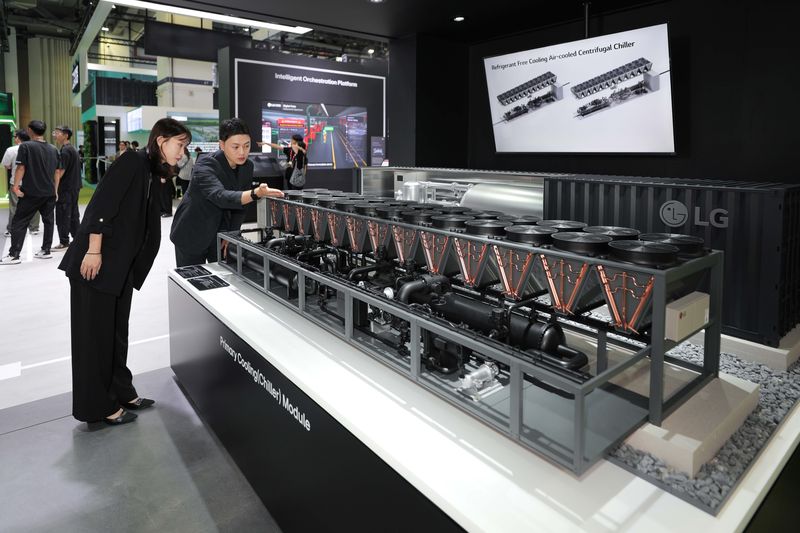
[Financial News] Korea Investment & Securities said investors should focus on the growth potential of LG Electronics’ AI data center cooling solutions business rather than its weak short-term earnings.
Although earnings came in below market expectations due to logistics cost pressures, the assessment is that there is significant room for medium- to long-term earnings improvement if better profitability in existing businesses coincides with strong growth in the cooling solutions business.
Hwang Jun-tae, an analyst at Korea Investment & Securities, maintained a Buy rating on LG Electronics and a target price of 265,000 won on the 29th. Based on the previous day’s closing price of 161,700 won, the potential upside is about 63.9%.
LG Electronics’ consolidated revenue for the third quarter was 23.8 trillion won, up 8.9% from the same period a year earlier. Operating profit rose 13.5% to 781.8 billion won but fell 26.1% short of market consensus. Operating profit from its standalone businesses, excluding LG Innotek, rose 98% year over year to 683.4 billion won, showing solid growth.
Hwang said, "With ocean freight rates remaining high, rising logistics costs are weighing on profitability." However, he forecast that as logistics costs gradually stabilize, profit growth in the core business would become more pronounced alongside improved profitability.
The key growth driver highlighted by Korea Investment & Securities is AI data center cooling solutions. LG Electronics’ new orders for cooling solutions in the first half of this year exceeded 600 billion won, while cumulative orders through the third quarter topped 3 trillion won.
The analysis said a long-term supply contract with Air Control Concept covering 5 GW of data center capacity is significant because it secures a stable revenue base for the coming years.
The product lineup is also expanding beyond its traditional focus on chillers to include CDUs, core equipment for liquid cooling. LG Electronics has secured approval from NVIDIA Corporation for CDUs rated at 600 kW, 1 MW and 2.6 MW.
Korea Investment & Securities estimated that chiller sales would exceed 1 trillion won this year, and forecast that chillers’ share of revenue in the Eco Solution (ES) division would rise from 8% in 2025 to at least 27% in 2027.
Improvements to existing businesses are another positive factor. The Vehicle Solution (VS) division has recorded operating margins in the mid-teens or higher for seven consecutive quarters, while the home appliance division is increasing the share of subscription revenue and easing seasonal earnings volatility.
Hwang said the AI data center cooling business had entered a phase in which expectations are translating into earnings. The analysis is that visibility into future earnings growth could improve as stronger earnings power in existing businesses combines with growth in new businesses.
[email protected] Kang Jung-mo Reporter