SKC Posts 49.6 Billion Won Q3 Operating Loss, 2.7 Times Market Forecast — Samsung Securities
- Input
- 2026-10-29 05:59:00
- Updated
- 2026-10-29 05:59:00
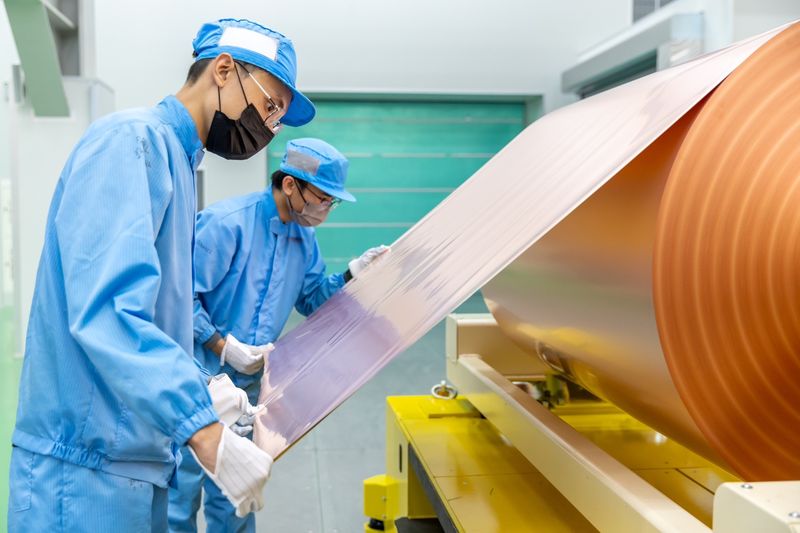
[Financial News] Although supply and demand conditions surrounding SKC’s copper foil business are believed to have improved and processing margins to have increased, the operating loss at its secondary battery materials division is expected to continue through the first half of next year. With this year’s third-quarter consolidated operating loss exceeding market expectations, Samsung Securities said it would maintain its ‘Hold’ rating and target price of 94,000 won until clear signs of a return to profitability emerge.
On the 29th, Samsung Securities said in a report analyzing SKC’s third-quarter results that the company’s performance was likely to improve next year, given improving supply and demand for copper foil and progress in glass substrate development. However, Cho Hyun-ryeol, a senior researcher at Samsung Securities, expected the secondary battery materials division to remain in operating loss through the first half of next year.
SKC posted a consolidated operating loss of 49.6 billion won in the third quarter, with its loss widening by 35.2 billion won from the previous quarter. This was also 31.3 billion won more than the market forecast of an 18.3 billion won operating loss. Revenue was 638.9 billion won, down 1.0% from the previous quarter but up 26.0% from the same period a year earlier. SK Nexilis, its copper foil subsidiary, posted an operating loss of 54.4 billion won, up 23.6 billion won from the previous quarter.
One-off costs incurred during the relocation of copper foil production facilities were the main factor behind the wider loss. SK Nexilis experienced temporary sales disruptions while suspending operations at its domestic plant. The fixed-cost burden from operating its Malaysia plant was also reflected in the results. Samsung Securities estimated that copper foil sales volume fell 1% from the previous quarter. SK Nexilis’s operating margin declined from -12.1% to -21.9%.
However, supply and demand for copper foil are reportedly improving. This is due to domestic battery makers expanding battery production for North American energy storage systems (ESS) and the limited expansion of global copper foil capacity over the past two to three years. Samsung Securities also estimated that SKC had raised its copper foil processing margins starting in the fourth quarter of this year. It forecast that SK Nexilis’s fourth-quarter sales volume would rise 20% from the previous quarter on strong ESS demand, and that its operating loss would narrow to 30.8 billion won as the higher processing margins took effect. SKC expects its Malaysia subsidiary to turn an operating profit in this year’s fourth quarter. Samsung Securities, however, estimated that SK Nexilis would remain loss-making overall, including its Malaysia subsidiary.
The semiconductor materials business posted operating profit of 21.8 billion won in the third quarter, up 2% from the previous quarter. Increased sales of high-value-added products related to artificial intelligence (AI) contributed to improved profitability. By contrast, operating profit in the chemicals business fell 56% from the previous quarter to 13.4 billion won, weighed down by weaker spreads for propylene glycol (PG) and styrene monomer (SM).
Samsung Securities forecast that SKC’s consolidated operating loss would narrow to 14.9 billion won in the fourth quarter. However, it expected the loss to be greater than the market forecast of 6.1 billion won. It estimated that SKC’s annual operating result would turn from a loss of 108 billion won this year to a profit of 53 billion won next year.
[email protected] Kim Mi-hee Reporter