“There’s no reason not to buy”: Samsung E&A raises full-year earnings target by 75% after surprise results... LG Innotek’s target price cut from ₩1.3 million to ₩530,000 [Stocktopia]
- Input
- 2026-10-23 11:10:19
- Updated
- 2026-10-23 11:10:19
[Financial News] Here is a roundup of reports from major securities firms on the morning of October 23.
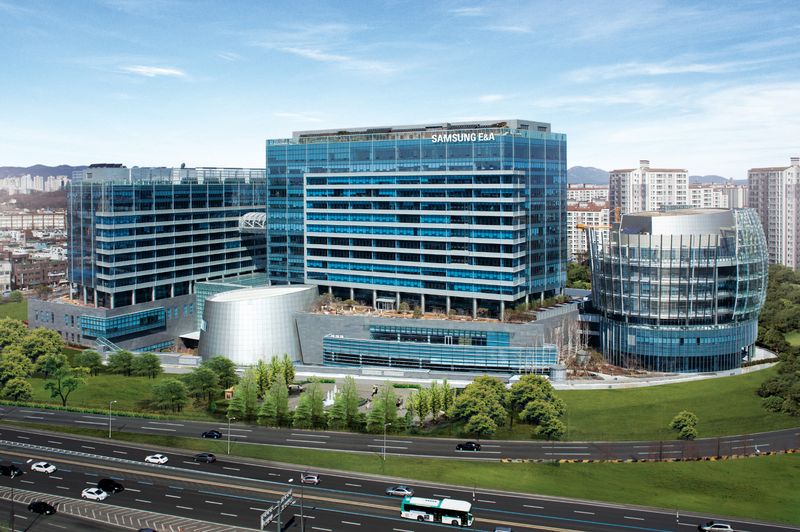
Samsung E&A was assessed as a potential investment alternative beyond the construction sector if business opportunities materialize as new orders next year, following its strong third-quarter results.
LG Innotek’s target price was sharply cut amid uncertainty over smartphone demand, but analysts say its current share price is in deeply oversold territory and investors should refocus on the value of its mid- to long-term substrate business. Celltrion was named the top pick among large-cap pharmaceutical and biotech stocks, with prescriptions expected to grow following the Japanese launch of its allergy treatment Omlyclo.
Samsung E&A: One-off gains translating into shareholder returns (Shinhan Securities)
◆ Samsung E&A (028050)― Shinhan Securities / Researcher Kim Seon-mi- Target price: ₩79,000 (up 16.2% from ₩68,000) | Previous day's close: ₩55,400
- Rating: Buy (maintained)
Shinhan Securities raised its target price for Samsung E&A to ₩79,000, saying the company had reported results twice market expectations in the third quarter and that the earnings outlook for next year and beyond had also improved.
Samsung E&A’s third-quarter operating profit was ₩500.6 billion, 100% above consensus. The result reflected increased sales to affiliates, a ₩100 billion recovery related to an arbitration settlement for the Yanbu power project, incentives from clients and gains from final project settlements. The company also raised its operating profit target for this year by 75%.
Researcher Kim Seon-mi said, “Strong earnings growth supported by orders from affiliates is encouraging, but the most positive development is that recurring one-off gains have led to a sustainable improvement in profitability and expanded shareholder returns.” She added that if business opportunities arising from the unstable external environment translate into increased new orders in 2027, the company “is expected to emerge as an irresistible investment alternative beyond the construction sector.”
She described the special dividend as “an expression of management’s confidence.” Analysts say that profits once considered one-off are now translating into sustainable profitability and shareholder returns, and that the company could be valued above construction stocks if new orders next year provide support.
LG Innotek: Focus on substrate value rather than short-term concerns (Hana Securities)
◆ LG Innotek (011070)― Hana Securities / Researcher Kim Min-kyung- Target price: ₩530,000 (down 59.2% from ₩1.3 million) | Previous day's close: ₩395,000
- Rating: Buy (maintained)
Hana Securities expects LG Innotek’s third-quarter results to fall short of market expectations due to exchange-rate effects and lowered its target price to ₩530,000 to reflect uncertainty over smartphone demand. It maintained its Buy rating, however.
Third-quarter operating profit is estimated at ₩90.7 billion, down 56% from the same period last year. The explanation is that the won’s sharp appreciation against the dollar coincided with a lag between raw-material purchases and their use in production, as well as inventory effects; concerns about mobile demand have also grown amid rising bill-of-materials (BOM) costs.
Researcher Kim Min-kyung said of flip-chip ball grid array (FC-BGA) substrates, “With the FC-BGA supply shortage continuing, LG Innotek is in the final stages of discussions with several global big tech companies on new capacity expansions and supply.” She judged that the current share price is “in deeply oversold territory, where investors should refocus on the value of the mid- to long-term substrate business rather than short-term concerns about mobile.”
The Package Solutions division is expected to contribute an increasing share of operating profit—29% in 2027 and 39% in 2028—reducing the company’s earnings sensitivity to changes in mobile demand.※ Flip Chip Ball Grid Array (FC-BGA) This is a high-value substrate that connects semiconductor chips to a mainboard. The chip is flipped over and bonded using solder balls. Its fast signal transmission and effective heat management make it suitable for high-performance semiconductors such as AI CPUs and GPUs.※ Bill of Materials (BOM) A BOM lists the types and quantities of components and raw materials used in a product. Applying unit prices to those items gives the BOM cost. Rising component prices put pressure on smartphone prices and can dampen demand.
Celltrion: Japan launch a springboard for business expansion (Daol Investment & Securities Co., Ltd.)
◆ Celltrion (068270)― Daol Investment & Securities Co., Ltd. / Researcher Lee Ji-su- Target price: ₩290,000 (up 3.6% from ₩280,000) | Previous day's close: ₩194,300
- Rating: Buy (maintained)
Daol Investment & Securities Co., Ltd. raised its target price for Celltrion to ₩290,000, citing expected new patient uptake and prescription growth following Omlyclo’s entry into Japan, and named the company its top pick among large-cap pharmaceutical and biotech stocks.
At the World Allergy Congress (WAC 2026), held in Kyoto, Japan, from the 15th to the 18th, Celltrion presented data showing that its omalizumab biosimilar Omlyclo is equivalent to the original drug, Xolair. Its price in Japan will be about 30% lower than that of the original drug. Celltrion plans to launch it for the 2027 hay fever (pollen-allergic rhinitis) season and then expand its indications to conditions including hives and asthma.
Researcher Lee Ji-su noted of Japan’s hay fever market, “There are many patients—four out of every 10 people in the country suffer from it—but Xolair prescriptions remain limited because the drug is reserved for severe patients whose condition is not controlled by existing treatments.” She added, “The significance of entering Japan lies less in short-term earnings than in expanding the business into allergy treatment and establishing a growth base for follow-on products.”
Analysts expect Omlyclo’s competitive pricing to attract severe patients who had put off treatment because of the cost, while the Japanese wholesaler network built through existing biosimilars will support its initial market entry.※ Biosimilar A biosimilar is a medicine developed after demonstrating equivalent efficacy and safety to a biologic whose patent has expired. Omlyclo is the first omalizumab biosimilar approved in South Korea, Europe, the United States and Japan.※ Indication An indication is a condition for which a particular medicine has been approved for use based on its therapeutic efficacy. In Japan, Omlyclo is approved for asthma, chronic urticaria and hay fever.
[Stocktopia]is an AI-powered stock-report briefing that compiles and delivers reports from major securities firms in South Korea. To keep receiving Jutopia, please subscribe to the reporter’s page.
[email protected] Seong Min-seo Reporter