"Samsung Electronics and SK hynix Have Bottomed Out... W-Shaped Rebound Possible in November–December" — KB Securities
- Input
- 2026-10-22 10:49:33
- Updated
- 2026-10-22 10:49:33
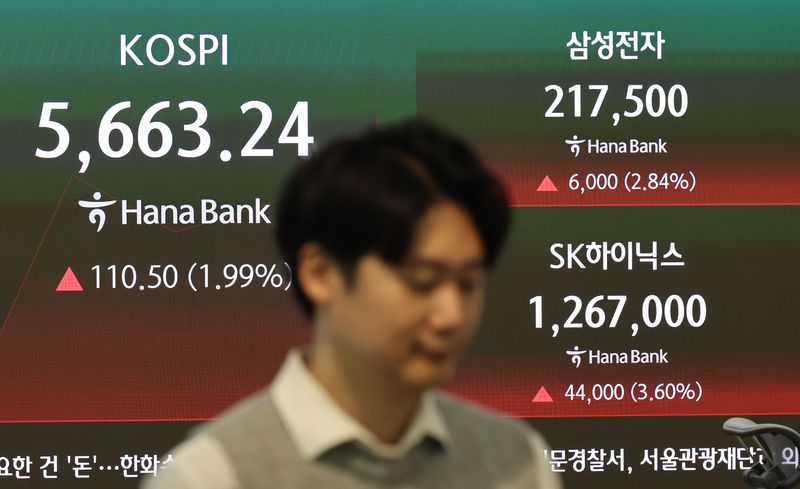
[Financial News] Another upbeat assessment of the semiconductor market has emerged. KB Securities said domestic semiconductor stocks, including Samsung Electronics and SK hynix, have entered a zone of excessive undervaluation relative to earnings following their recent sharp declines, and that investors should focus on the possibility of a rebound in November and December.
Kim Dong-won, head of research at KB Securities, said in a report on the 22nd, “The KOSPI appears to have confirmed a W-shaped bottom, having formed lows twice, on July 29 and October 15,” adding, “It appears to have passed the peak of concern.”
The main reason for expecting a rebound is that stock prices have fallen excessively relative to earnings. KB Securities analyzed that the estimated price-to-earnings (P/E) ratios based on 2027 earnings are 3.3 times for Samsung Electronics and 2.7 times for SK hynix, lower even than during the past financial crisis.
By contrast, it viewed demand for artificial intelligence (AI), a key driver of semiconductor earnings, as still robust. With demand for AI servers continuing and demand for AI semiconductors expected to exceed supply through 2028, the recent weakness in stock prices is difficult to interpret as a sign of slowing earnings, it said.
It assessed that external factors that have weighed on stock prices may also gradually ease. Kim noted, “The U.S. 10-year Treasury yield appears to have passed its short-term peak, and concerns about the financial health of AI data center companies have also been substantially priced into stock prices.”
One short-term variable is the U.S. midterm elections, to be held on the 3rd of next month. However, he predicted that even if the Democratic Party were to gain control of Congress, investment in AI infrastructure itself would be unlikely to contract significantly, given the broader trend of U.S.-China AI competition.
Kim said, “The market’s focus is expected to shift from interest rates to inflation, and from supply and demand to earnings,” and forecast, “In November and December, a W-shaped rebound will begin as the unusual gap between earnings and valuations narrows.”
[email protected] Kim Hee-sun Reporter