“A law that protects only controlling shareholders”: Petition opposing mandatory tender offer system tops 40,000
- Input
- 2026-10-21 11:31:29
- Updated
- 2026-10-21 11:31:29
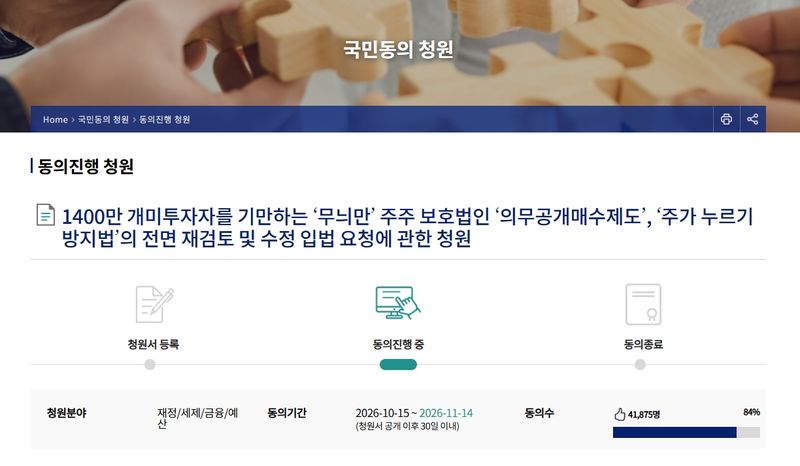
[Financial News] Opposition from individual investors to the mandatory tender offer system and the so-called “stock-price suppression prevention law,” both being pursued to protect minority shareholders and address the Korea discount, is intensifying. A National Assembly e-petition calling for a full review of the relevant bills has received support from at least 40,000 people in just six days since it was launched.
According to the National Assembly e-Petition website on the 21st, around 42,000 people had supported the petition by that morning. Launched on the 15th, it calls for a full review and legislative revision of the mandatory tender offer system, described as a shareholder-protection law in name only that deceives 14 million retail investors, and the stock-price suppression prevention law. That amounts to 84% of the 50,000 supporters required for referral to the relevant standing committee of the National Assembly.
The petitioner argued that “bills introduced under the principle of investor protection to advance the capital market and address the Korea discount are straying from their original purpose and instead turning into bad laws that legally protect only the interests of controlling shareholders.” The petitioner said they “must be fully reconsidered as fair and effective bills that align with the original aim of protecting minority shareholders.”
The petitioner pointed out that ordinary shareholders are unlikely to receive adequate protection under the mandatory tender offer system being pursued by the National Assembly. A mandatory tender offer gives ordinary shareholders, as well as the largest shareholder, the opportunity to sell their shares at a price that includes a control premium during a merger or acquisition (M&A).
An amendment to the Financial Investment Services and Capital Markets Act that cleared the National Assembly’s National Policy Committee makes cases including the acquisition of a 25% or larger stake in a listed company, resulting in the acquirer becoming its largest shareholder, subject to a mandatory tender offer. It requires the acquirer to make a tender offer for ordinary shareholders’ shares until its total holdings, including shares already acquired, reach 50% plus one share of all issued shares.
The petitioner argued that a “100% mandatory tender offer system” should be introduced. He criticized the bill, saying, “There is no other country in the world where, in an acquisition of ‘50%+1 share,’ the law first requires the purchase of only the controlling shareholder’s stake,” and that it “imposes ‘legal immunity’ on controlling shareholders and ‘legal unfairness’ on minority shareholders.”
He argued that if the “50%+1 share” threshold is retained, the bill should be revised so that the acquirer purchases shares from both controlling and minority shareholders on an equitable basis.
Questions were also raised about the stock-price suppression prevention law. The measure refers to an amendment to the Inheritance and Gift Tax Act aimed at preventing controlling shareholders from deliberately keeping stock prices low to reduce their inheritance and gift tax burden.
The petitioner argued that 80% of net asset value should be the floor when calculating inheritance and gift taxes. The petitioner’s position is that the government proposal has lost effectiveness because it includes eligibility requirements such as being in the bottom 25% of one’s industry for six consecutive years.
The petitioner stressed that “the value of each share in the stock market should be fair and equal,” adding, “We must no longer allow a market where one share held by a controlling shareholder is worth its weight in gold, while one held by a minority shareholder is treated as dirt.”
The petitioner went on to urge lawmakers: “Please revise the mandatory tender offer system and the stock-price suppression prevention law to make them effective, robust shareholder-protection measures, so that the domestic stock market can become a market trusted by both domestic and foreign investors.”
[email protected] Seo Min-ji Reporter