Global Top 100 Auto Parts Suppliers Post $939.6 Billion in Revenue... Chinese CATL and India’s Motherson Shake Up the Rankings
- Input
- 2026-10-21 11:00:00
- Updated
- 2026-10-21 11:00:00
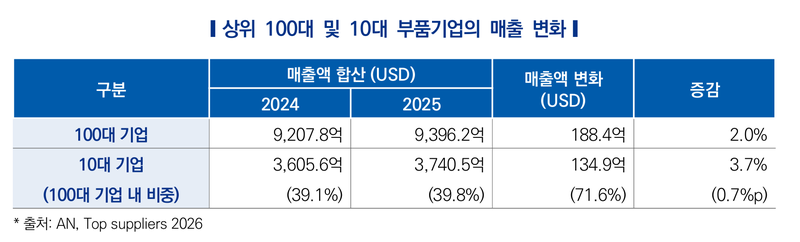
■ Top 10 companies drive growth... Rankings shift as CATL and Motherson make gains
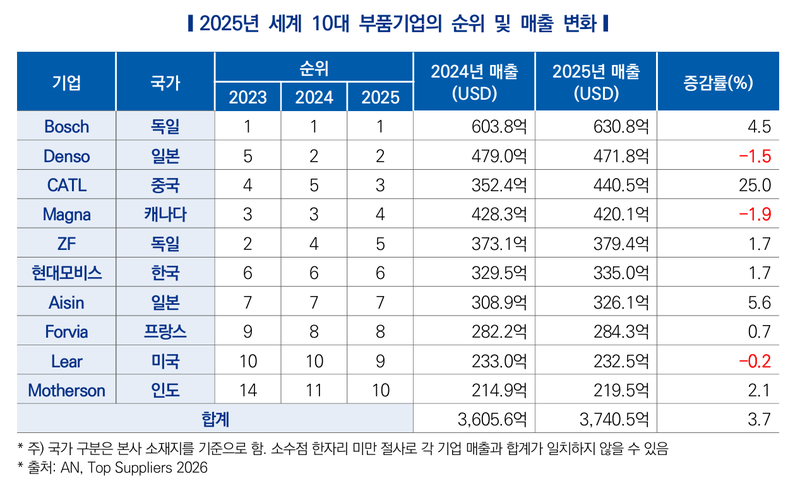
The rankings near the top changed modestly but noticeably. Germany’s ZF Friedrichshafen AG (ZF) fell from second place in 2023 to fifth last year as it restructured its business, including pursuing the sale of its advanced driver-assistance systems (ADAS) business. Germany’s Continental AG spun off its automotive division, excluding tires, as AUMOVIO last September, and its ranking fell from ninth to 38th; the newly separated AUMOVIO ranked 11th. By contrast, China’s CATL saw revenue surge 25.0% year over year, climbing two places to third, while India’s Motherson entered the top 10 for the first time, buoyed by revenue growth and the effect of Continental’s separation of AUMOVIO.
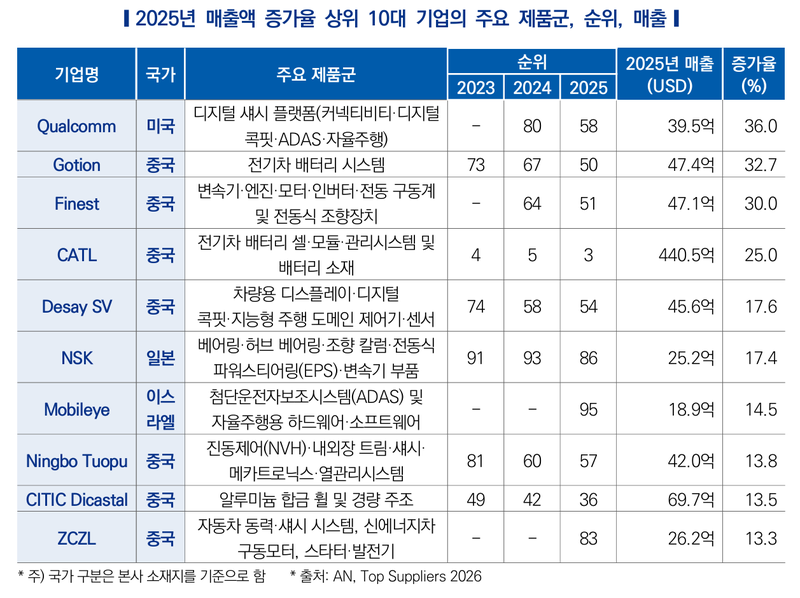
Companies focused on electrification and smart technologies stood out in terms of revenue growth. The leading growth rates were posted by Qualcomm (36.0%), Gotion (32.7%), Pineest (30.0%), CATL (25.0%) and Desay SV (17.6%), respectively. Of the top 10 companies by growth rate, six were classified as related to electrification and three as related to smart technologies. Notably, seven of the 10 were Chinese companies, indicating that the parts ecosystem is also expanding rapidly alongside the growth of Chinese automakers.
■ Asia accounts for the largest share at 39.4%... Revenue at nine Korean companies up 2.3%
The number of companies in the top 100 rose from 14 to 16 in China, while it edged down in the United States (17 to 16), Germany (16 to 15) and South Korea (10 to 9). The report said South Korea’s decline was due to SK On’s merger with SK Enmove, which led to its exclusion from the tally of sales to automakers, and should not be seen as a result of declining competitiveness. China posted the highest increase in combined revenue by country, at 16.2%, followed by South Korea (2.3%), the United States (0.9%) and Germany (0.8%); Japan’s total fell 1.2%.
The combined revenue of the nine companies based in South Korea rose 2.3%, from $73.29 billion to $74.97 billion, accounting for 8.0% of the total. Hyundai Mobis held on to sixth place with revenue of $33.5 billion, while Hyundai Transys climbed from 31st to 27th as its revenue increased 9.7%. Hanon Systems (up 4.4%) and Seoyon E-Hwa (up 6.9%) also recorded growth, while Hyundai Wia’s revenue fell 7.0%.
The report forecast that growth centered on electrification and smart technologies would continue. In China, production is rising and the parts ecosystem is growing alongside it, as exports expand despite slower domestic growth. However, with restrictions on imports and other countermeasures, including tariffs, intensifying particularly in Europe, export growth is expected to gradually slow, while companies may increasingly expand into local production, the report said.
Oh Jin-woo, a researcher at the Industrial Research Office who authored the report, said, “We expect Chinese automakers and the overseas businesses of parts suppliers joining their localization efforts to expand, but at the same time, procurement from local parts suppliers is also expected to increase under pressure from local governments.” He predicted, “Parts suppliers with a track record of supplying Chinese automakers will be able to secure additional supply opportunities as a result of this localization trend.”
[email protected] Dongchan Kim Reporter