POSCO Future M seeks to issue up to 200 billion won in bonds amid financial strain [fn Market Watch]
- Input
- 2026-10-19 13:56:15
- Updated
- 2026-10-19 13:56:15
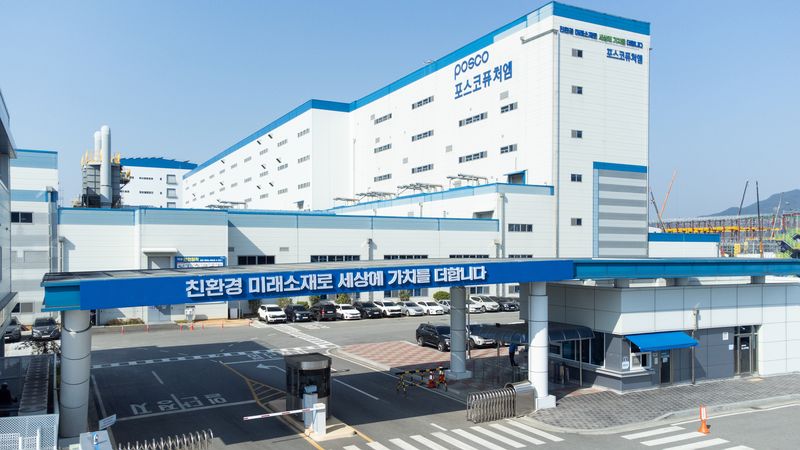
According to investment banking (IB) industry sources on the 19th, POSCO Future M plans to hold a bookbuilding for institutional investors on the 4th of next month for its bond issuance. It will seek a total of 100 billion won in 2- and 3-year bonds, with plans to increase the amount to as much as 200 billion won depending on the results of the bookbuilding. The bonds are scheduled to be issued on Nov. 12.
The five lead managers are NH Investment & Securities, KB Securities, Korea Investment & Securities, Kiwoom Securities and Samsung Securities Co., Ltd. The company plans to set the indicative pricing range at -30 bp to +30 bp relative to the individual issue’s evaluated yield (1 bp = 0.01 percentage point).
POSCO Future M also raised funds in the public corporate bond market in January this year. At the time, institutional investors placed orders totaling 630 billion won for a 250 billion won offering, but the final yields on the 3- and 5-year bonds were set 18 bp and 24 bp above their respective individual issue evaluated yields. In effect, borrowing costs included a premium despite investor demand exceeding the amount offered.
The size of institutional investors’ orders and the final yield are both emerging as key points of interest in this bookbuilding. In particular, with a pricing band of 30 bp on either side of the individual issue’s evaluated yield, the key question is how much of POSCO Future M’s financial burden the market will reflect in the yield.
POSCO Future M has an AA-/Stable credit rating. However, the increased debt burden following large-scale capital expenditures is considered a key factor in managing its credit profile.
According to rating trigger data from credit rating agencies, POSCO Future M’s total debt/EBITDA (earnings before interest, taxes, depreciation and amortization) stood at 14.8x as of the end of June this year. This is well above the 8x threshold for a downgrade review set by NICE Investors Service.
Total debt/EBITDA indicates how large a company’s borrowings are relative to the cash earnings it generates through operating activities. The higher the figure, the greater the debt repayment burden relative to its ability to generate operating cash flow.
POSCO Future M’s ratio surged from 5.4x in 2021 and 5.7x in 2022 to 17.3x in 2023. It rose further to 19.8x in 2024, before falling to 16.8x last year and 14.8x as of the end of June this year. Despite the improvement, it remains substantially above the rating agencies’ downgrade review threshold.
By contrast, profitability indicators are showing signs of recovery. The EBITDA-to-sales ratio rose from 3.6% in 2023 to 8.0% last year and 9.8% as of the end of June this year, approaching the 10% threshold for an upgrade review set by the credit rating agency.
Profitability is recovering, but improvement in the company’s ability to repay debt has been relatively slow. However, exceeding a rating trigger with an individual financial metric does not automatically result in a credit rating adjustment. Credit rating agencies determine ratings by taking into account business competitiveness, future cash flows and financial policies, among other factors.
Ultimately, the bookbuilding is expected to offer an opportunity to see how the bond market assesses POSCO Future M’s recovering performance and its still-high debt burden.
[email protected] Kim Hyun-jung Reporter