Hanwha Systems’ target price trimmed slightly on Philly Shipyard divestment ... Daeduck Electronics’ Q3 operating profit seen surging 232% [Stocktopia]
- Input
- 2026-10-19 11:04:35
- Updated
- 2026-10-19 11:04:35
[Financial News] Here is a roundup of reports from major securities firms on the morning of October 19.
Hanwha Systems’ target price was trimmed slightly to reflect the sale of Philly Shipyard, but its third-quarter results are expected to beat market expectations. The Cheongwang laser air-defense weapon and low-Earth-orbit satellites are also seen as drivers of medium- to long-term growth.
LIG Defense & Aerospace (LIG D&A) is expected to post third-quarter operating profit below market expectations, though its medium- to long-term growth prospects remain intact. Daeduck Electronics is expected to beat market expectations in the third quarter, while higher prices for memory substrates are seen as an additional factor for improvement in the fourth quarter.
Hanwha Systems: More value should be assigned to its space business (Daishin Securities)
◆ Hanwha Systems (272210)― Daishin Securities / Research Analyst Choi Jeong-hwan- Target price: KRW 98,000 (cut 4.9%, from KRW 103,000) ᅵ Previous day's close: KRW 80,500
- Investment rating: Buy (maintained)
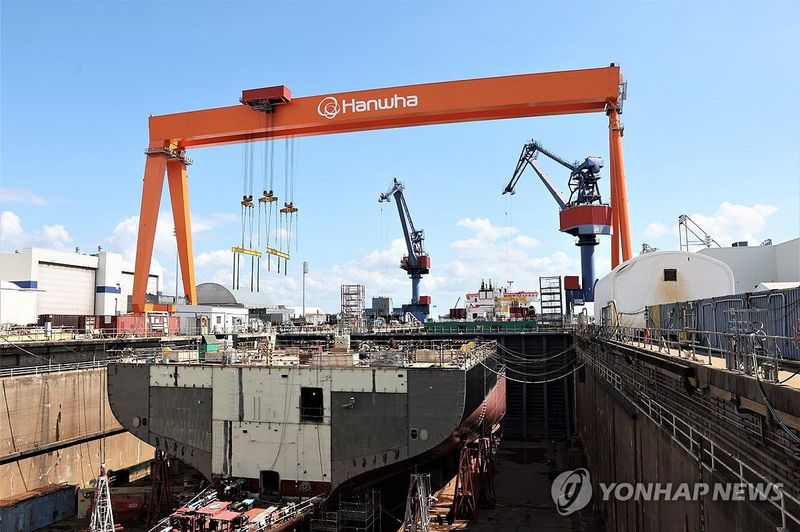
Daishin Securities slightly lowered its target price for Hanwha Systems to KRW 98,000, excluding the value of its shipbuilding business from its valuation to reflect the ongoing sale of Philly Shipyard, even as it expects the company to post results above market expectations in the third quarter. It estimated third-quarter operating profit at KRW 71 billion, up 223% year on year and above the consensus estimate of KRW 60 billion.
Research analyst Choi Jeong-hwan expects the export share to rise from 22.9% in the second quarter to 36.6% in the third quarter as progress accelerates from the second half on the Cheongung-II multifunction radar (MFR) projects in the United Arab Emirates (UAE) and Saudi Arabia, while losses at Philly Shipyard are also expected to narrow from the second quarter. However, he explained, “It is unclear whether Philly Shipyard’s results will be classified as discontinued operations in the third quarter while the sale is underway, so we have included them in our consolidated estimates through this quarter.”
Choi said Hanwha Systems is “transforming from a subsystem supplier into a systems integrator through Cheongwang and low-Earth-orbit satellites.” He added, “Domestic mass production of Block 1 of the Cheongwang laser air-defense weapon is underway. It is expected to develop into a higher-output, mobile system through in-house development and upgrades through Block 3, and is attracting interest in Eastern Europe and the Middle East.”
He added, “Through the Jeju Hanwha Space Center, which has an annual production capacity of 100 satellites, the space business plans to pursue low-Earth-orbit satellite exports, satellite leasing and imagery services.” He expects the value of the space business to be reflected further in the share price, “as the company moves up from supplying individual equipment to designing and integrating entire weapons systems.”※ Cheongwang (Block I laser air-defense weapon)This domestically developed laser weapon uses a high-power fiber laser to intercept small drones and other unmanned aircraft. It was developed by the Agency for Defense Development, with Hanwha Systems participating as the prototype contractor. It was deployed operationally for the first time in the world in late 2024, and has drawn attention as a counter-drone weapon because each shot costs only about KRW 2,000.※ Multifunction radar (MFR, Multi-Function Radar)This equipment uses a single radar to detect and track targets and guide missiles. It is a key component of the Cheongung-II system and is supplied by Hanwha Systems. Revenue recognition from exports to the Middle East is considered a factor driving improved results.
LIG D&A: Growth remains intact despite near-term pressures (Daishin Securities)
◆ LIG D&A (079550)― Daishin Securities / Research Analyst Choi Jeong-hwan- Target price: KRW 830,000 (cut 16.2%, from KRW 990,000) ᅵ Previous day's close: KRW 580,000
- Investment rating: Buy (maintained)
Daishin Securities cut its target price for LIG D&A to KRW 830,000, expecting third-quarter operating profit to fall 8.9% year on year to KRW 80 billion, below the consensus estimate of KRW 100 billion. The revision followed a shift in the price-to-earnings (P/E) valuation year from 2028 to 2027 and a reduction in its 2027 earnings estimate.
With development costs concentrated in the fourth quarter and provisions for losses expected on the award of a domestic long-range air-to-air missile development contract, the firm estimated this year’s operating margin at 7.5%, below the company’s 8.0% target.
The Buy rating was maintained despite this because of the share price level. Research analyst Choi Jeong-hwan said the 2027 P/E of 20.7 times had “fallen below the global peer multiple of 24.1 times, putting the stock in undervalued territory.”
The firm also expects the company to expand the countries it exports to for products such as the M-SAM medium-range surface-to-air missile system and the L-SAM long-range surface-to-air missile, while continuing to grow rapidly on the back of existing orders. The company plans to meet demand for air-defense weapons by expanding its Gimcheon and Gumi plants, though some of the additional capacity at the Gimcheon plant, due for completion in early 2027, is expected to be reflected in results from the second half of that year.
The company is also pursuing the establishment of a joint venture with Germany’s Rheinmetall AG to develop European versions of the M-SAM and L-SAM over the medium to long term. Choi expects that as the systems expand in Europe, “demand for related components could rise at the same time, boosting other export revenue as well.”※ Cheongung-II (M-SAM, medium-range surface-to-air guided missile)This domestically developed defensive guided missile intercepts aircraft and ballistic missiles at medium altitudes, forming a multilayered defense network alongside the L-SAM at a different altitude. Exported to Middle Eastern countries including the UAE and Saudi Arabia, it is a key contributor to LIG D&A’s overseas sales.※ Long-range surface-to-air guided missile (L-SAM, El-Sam, Long-Range Surface-to-Air Missile)This defensive guided missile intercepts ballistic missiles and aircraft approaching at high altitudes. Also known as the “Korean THAAD,” it is a system separate from the Cheongung series.※ Close-in weapon system (CIWS, Close-In Weapon System)This ship-defense weapon intercepts anti-ship missiles and aircraft approaching a vessel at the final stage. It is considered a product with potential for expanded overseas supplies alongside ship exports.
Daeduck Electronics: This substrate price increase is different in nature (iM Securities)
◆ Daeduck Electronics (353200)― iM Securities / Research Analyst Go Ui-young- Target price: KRW 190,000 (maintained) ᅵ Previous day's close: KRW 131,700
- Investment rating: Buy (maintained)
iM Securities maintained its KRW 190,000 target price for Daeduck Electronics, expecting third-quarter operating profit to surge 232% year on year to KRW 81.2 billion, 6% above market forecasts. The firm said improvements in utilization at Flip Chip Ball Grid Array (FC-BGA), a high-value semiconductor packaging substrate, and the impact of expanded multilayer printed circuit board (MLB) capacity were stronger than expected.
Research analyst Go Ui-young estimated that third-quarter operating profit would have reached around KRW 90 billion if not for the decline in the won-dollar exchange rate. Higher prices for memory packaging substrates were cited as an additional factor for improvement in the fourth quarter.
Go said, “If the price increase in April passed on higher raw-material costs, this increase is based on tight supply and demand.” The point is that an increase driven by supply shortages could lead to improved profitability.
The firm also highlighted plans to wrap up discussions on long-term supply agreements (LTAs) for FC-BGA with multiple customers by year-end. Go explained, “The introduction of long-term revenue guidance, which the company has not had before, could itself be a catalyst.”※ Flip Chip Ball Grid Array (FC-BGA)This high-value substrate connects semiconductor chips to a motherboard by flipping the chip over and bonding it with solder balls. It enables faster signal transmission and better heat management, and is used in high-performance semiconductors such as CPUs and GPUs for AI applications.※ Multilayer printed circuit board (MLB, Multi-Layer Board)This is a high-layer-count printed circuit board made by stacking multiple circuit layers, and is used in high-performance equipment such as servers and network devices. Daeduck Electronics is improving profitability by filling its expanded capacity with products for the aerospace and defense sectors.
[Stocktopia]is an AI-based stock report briefing that compiles reports from major securities firms in South Korea. To keep receiving [Stocktopia], please subscribe to the reporter’s page.
[email protected] Seong Min-seo Reporter