“Buldak Holds Firm”: Samyang Foods Keeps 1.75 Million Won Target Despite Stronger Won; S1 Target Price Raised 31% on 134% Shareholder Return Ratio [Stocktopia]
- Input
- 2026-10-16 11:19:10
- Updated
- 2026-10-16 11:19:10
[Financial News] Here is a roundup of reports from major securities firms on the morning of October 16.
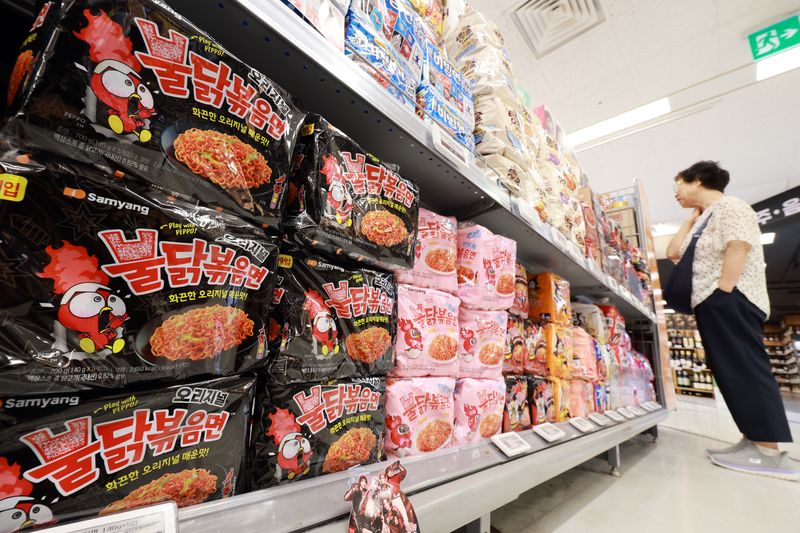
Samyang Foods was named the top pick in the food and beverage sector, with analysts saying that top-line growth is expected to continue as utilization at its second Miryang plant increases and its China plant expands, while overseas demand remains solid despite concerns over the stronger won.
Korean Air posted results befitting the peak season on a standalone basis in the third quarter, but its Hold rating was maintained due to the burden from subsidiaries and rising oil prices. S1’s rating was raised to Buy, with analysts expecting a reassessment of its corporate value on the back of a shareholder-return policy centered on a tender offer for its own shares and their cancellation.
Samyang Foods: A Model for Korea’s Food and Beverage Market (Shinhan Investment & Securities)
◆ Samyang Foods (003230)— Shinhan Investment & Securities / Research Fellow Jo Sang-hoon- Target price: 1.75 million won (maintained) | Previous closing price: 1,151,000 won
- Rating: Buy (maintained)
Shinhan Investment & Securities expects Samyang Foods to post results in line with third-quarter market expectations, as overseas demand remains solid despite concerns that the stronger won will weigh on earnings. It maintained its target price of 1.75 million won and its designation of the company as the food and beverage sector’s top pick. Third-quarter operating profit is estimated at 186.3 billion won, up 42.3% year on year.
Research Fellow Jo Sang-hoon described Samyang Foods as “a model in Korea’s food and beverage market, where the limits to growth have become clear.” He added that “concerns about slower growth due to the stronger won can be minimized through high gross margins, low price sensitivity and strong brand power.”
He identified expanded production capacity as key to medium- and long-term growth. “All three lines for bagged noodles at the second Miryang plant are currently running 24 hours a day, while the two cup-noodle lines are operating on two shifts,” Jo said. “Further increases in utilization are expected as all lines move to two-shift operations in the second half of the year.”
Samyang Foods also changed its plan for the China plant, increasing the number of production lines from six to eight. Jo called this “a response to stronger-than-expected demand.” He expects total production capacity to expand by an additional approximately 43% once the China plant is completed at the end of this year.
The 9.9% decline in the share price over the past month was also viewed positively. “The recent share-price correction has eased valuation concerns somewhat,” Jo said. He added, “We are at the beginning of a period of expanding overseas momentum, and it is important to note that the company’s higher growth is expected to persist for a long time compared with competitors currently experiencing negative growth in the U.S.”
Korean Air Maintains Hold Despite Peak-Season Results (Samsung Securities)
◆ Korean Air (003490)— Samsung Securities / Researcher Kim Young-ho- Target price: 32,000 won (maintained) | Previous closing price: 29,450 won
- Rating: Hold (maintained)
Samsung Securities maintained its target price of 32,000 won and Hold rating for Korean Air, which posted record-high quarterly revenue on a standalone basis in the third quarter, citing the burden from subsidiaries and rising oil prices. Korean Air’s standalone third-quarter revenue surged 26% year on year to 5.0448 trillion won, while operating profit rose 12% to 421.2 billion won.
Researcher Kim Young-ho described the results as “standalone performance befitting the peak season,” but noted that “international revenue increased 22% year on year and cargo revenue also surged 34%, while operating profit rose just 12% due to higher cost burdens, including rising oil prices.”
The key issue is the consolidated performance, which includes Asiana Airlines and its subsidiaries. Kim said, “Given Asiana Airlines and the low-cost carrier (LCC) subsidiaries, it is difficult to be confident that consolidated results will be as strong as standalone results.” The firm raised its operating-profit estimate for this year by 12%, while keeping its target price and rating unchanged.
The burden of oil prices is also growing. Kim warned that “geopolitical risks in the Middle East are worsening amid escalating military clashes between Saudi Arabia and Yemen’s Houthi rebels.” He added that “West Texas Intermediate (WTI) crude has again topped $95 a barrel, while the jet fuel crack spread (jet fuel price minus crude oil price) has exceeded $70, a record high.”※ Jet Fuel Crack SpreadThis is the price of jet fuel minus the price of crude oil, and represents the margin refiners earn by processing crude into jet fuel. The wider the spread, the more it is seen as a factor that increases airlines’ fuel costs by more than the rise in crude oil prices.
S1 Seen Poised for Revaluation as Shareholder Returns Gather Pace (LS Securities Co., Ltd.)
◆ S1 (012750)— LS Securities Co., Ltd. / Researcher Kim Se-ryeon- Target price: 115,000 won (raised 30.7%, from 88,000 won) | Previous closing price: 97,600 won
- Rating: Buy (raised from Neutral)
LS Securities Co., Ltd. raised its rating on S1 to Buy and its target price to 115,000 won, saying that the company’s shareholder-return policy, including large-scale share buybacks and cancellations, is expected to prompt a reassessment of its corporate value.
S1 proposed a tender offer to buy back its own shares at 99,000 won per share and announced plans to achieve a cumulative shareholder-return ratio of 134% over the three years through 2028 by combining share buybacks and cancellations with dividends. The number of shares outstanding, currently 37.99 million, is expected to fall to around 29.26 million after the second share cancellation.
Researcher Kim Se-ryeon said, “S1 has been a stock with high expectations for shareholder returns, given its stable and steady earnings growth, strong net cash position and potential to make use of treasury shares. Its proactive shareholder-return stance is expected to provide positive share-price momentum for the time being.” She added, “Considering the improvement in return on equity (ROE) through future buybacks and cancellations, as well as the earnings turnaround in 2027, the share price still has ample room to rise further.”
Third-quarter operating profit rose 5.3% year on year to 65.4 billion won, in line with market forecasts. Profit at the high-margin security systems integration (SI) business continued to decline amid a lull in orders, but the building management business maintained double-digit growth, helping support results in the infrastructure division, analysts said.
[Stocktopia]is an AI-powered stock-research briefing that gathers and shares reports from major domestic securities firms. To keep receiving Stocktopia, please subscribe to the reporter’s page.
[email protected] Minseo Seong Reporter