HK inno.N Corp.'s U.S. approval momentum remains intact; target price: KRW 67,000
- Input
- 2026-10-13 08:20:37
- Updated
- 2026-10-13 08:20:37
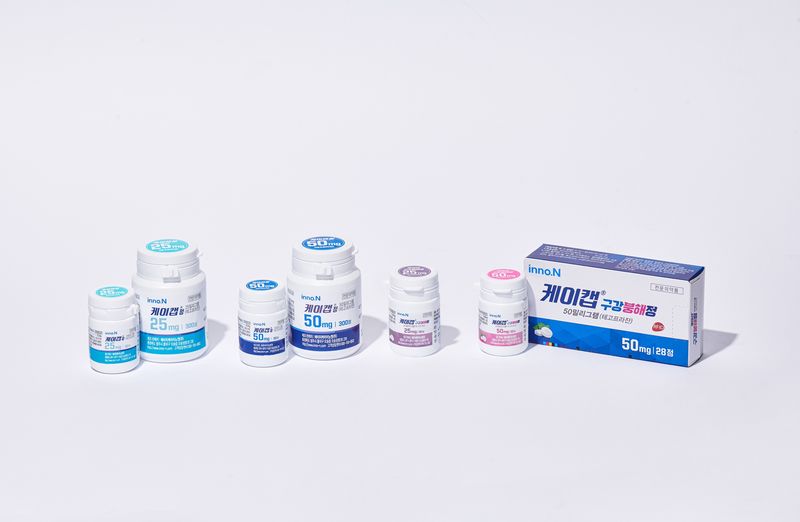
[Financial News] Daol Investment & Securities forecast that HK inno.N Corp.'s third-quarter results would fall short of market expectations, due to factors including adjustments to domestic K-CAB shipments and lower royalties from China.
However, it said medium- to long-term growth drivers, including U.S. product approval for K-CAB and the possibility of a technology transfer in Europe, remained intact, and maintained its Buy rating and target price of KRW 67,000.
On the 13th, Lee Ji-su, a researcher at Daol Investment & Securities, estimated HK inno.N Corp.'s third-quarter revenue at KRW 267.6 billion and operating profit at KRW 25.6 billion.
Revenue was expected to rise 2.6% year on year, while operating profit was expected to fall 1.0%. Both figures were below market consensus: revenue of KRW 273.7 billion and operating profit of KRW 31 billion.
Domestic K-CAB revenue was forecast to rise just 0.5% year on year to KRW 44 billion, reflecting drug price cuts, deductions related to reimbursed products, and adjustments to shipments through distribution channels.
Royalties from China were also expected to decline quarter on quarter as local pharmaceutical sales and prescribing activity weakened. Condition, the hangover remedy, was expected to remain loss-making amid a shrinking market and additional advertising spending in the third and fourth quarters.
However, analysts see the possibility of improved results starting in the fourth quarter. Daol Investment & Securities forecast fourth-quarter revenue of KRW 287.7 billion and operating profit of KRW 127.6 billion, based on a recovery in domestic K-CAB sales and the recognition of royalties from China. For the full year, it expected revenue of KRW 1.0877 trillion and operating profit of KRW 127.6 billion.
The key investment thesis is K-CAB's entry into the U.S. market. In a U.S. Phase III trial for nonerosive gastroesophageal reflux disease (NERD), K-CAB showed greater improvement in heartburn than a placebo, with the effect lasting up to 24 weeks during extended treatment.
Detailed data will be presented at the American College of Gastroenterology (ACG). Daol Investment & Securities expects U.S. product approval in 2027 and said negotiations for a technology transfer in Europe are also progressing smoothly.
Lee said expectations for U.S. approval and a technology transfer in Europe remained valid despite short-term factors affecting results, including adjustments to domestic shipments, lower royalties from China, and advertising costs. Accordingly, the firm maintained its Buy rating and target price of KRW 67,000.
[email protected] Kang Jung-mo Reporter