“Cosmax’s third-quarter earnings to significantly exceed market forecasts ... target price raised”
- Input
- 2026-10-07 09:20:52
- Updated
- 2026-10-07 09:20:52
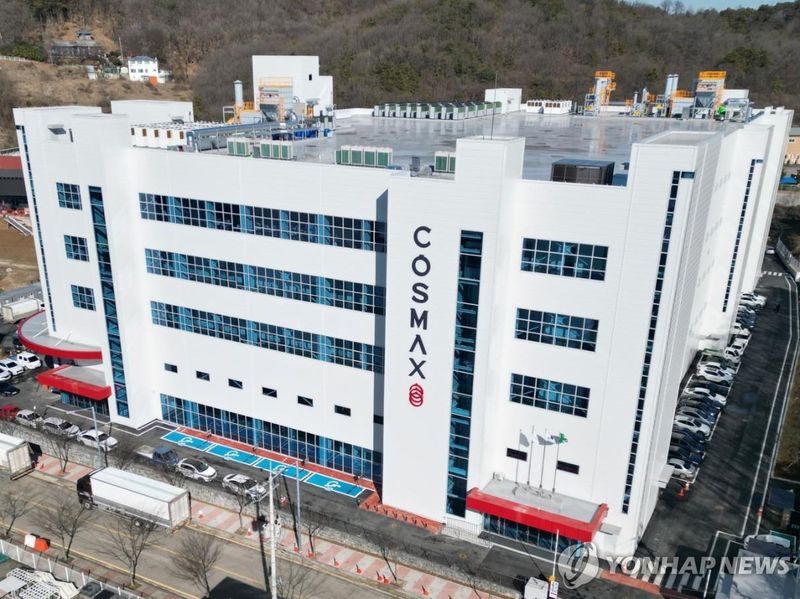
[Financial News] Hana Securities said on the 7th that Cosmax would post earnings above market expectations in the third quarter of this year, driven by domestic and overseas sales growth. It maintained its “Buy” rating and raised its target price by 24.6%, from 305,000 won to 380,000 won.
Hana Securities analyst Park Jong-dae said, “Third-quarter consolidated revenue and operating profit are expected to come in at around 823.8 billion won and 79 billion won, up 41% and 85%, respectively, from a year earlier,” adding, “This would be a strong performance, significantly exceeding the market’s operating profit forecast of 67.7 billion won.”
He expected growth at the domestic headquarters to drive improved results. Analyst Park said, “The domestic headquarters is expected to break away from seasonal trends and post higher sales than in the second quarter. Exports of indie brands are very strong, and contributions from global MNCs and overseas indie brands are increasing.”
He added, “With a higher share of skincare products, a recovery in the color cosmetics category and improved gel-mask efficiency, domestic operating profit is expected to rise 78% year on year and exceed 60 billion won for the first time in a quarter.”
Among its overseas subsidiaries, he viewed the normalization of the U.S. business positively. Analyst Park said, “In the U.S., steady reorder volumes from local indie and legacy clients are continuing, while new orders are also rising significantly. Indie brands in particular are contributing more to sales, and toner pads, eye patches and hydrogel masks are popular.”
He also forecast continued growth at the subsidiaries in China and Southeast Asia. “The Shanghai subsidiary in China is expected to grow 30% year on year, led by large local clients, while Guangzhou is expected to post top-line growth of more than 20% on the back of strong offline and export channels. In Thailand, new clients from neighboring countries are joining at an increasing rate, in addition to major clients,” he said.
Analyst Park said, “The second-quarter results eased a range of uncertainties through improved domestic profitability, a return to operating profit in the U.S. business and a turnaround in Southeast Asia.” He added, “We expect the third-quarter results to demonstrate that the company is breaking the seasonality of a stronger first half and weaker second half, as momentum for K-beauty globally expands and the benefits of being the world’s No. 1 ODM company begin to materialize in earnest.”
[email protected] Joo Won-gyu Reporter