Hankuk Carbon, Taekwang Industrial Near Stalking-Horse Selection for K Shipbuilding [fn Market Watch]
- Input
- 2026-10-07 13:27:14
- Updated
- 2026-10-07 13:27:14
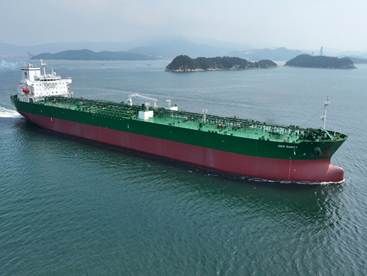
[Financial News] The selection of Hankuk Carbon and Taekwang Industrial, which have entered the race to acquire mid-sized shipbuilder K Shipbuilding, as conditional prospective buyers under a stalking-horse arrangement is imminent. They are understood to have begun working-level procedures to sign an MOU with the sellers, UAMCO (United Asset Management Company) and KHI.
The previous sale fell through in part because of a judgment that it would be difficult to secure credit enhancement for refund guarantees on advance payments (RG) through a fund managed by Green Harbor Asset Management. This time, Taekwang Industrial plans to make proper preparations for RG credit enhancement by having Hankuk Carbon, which makes the cryogenic insulation materials used in LNG carrier cargo holds, join forces with Taekwang.
According to investment banking (IB) industry sources on the 7th, UAMCO, KHI and Samil PricewaterhouseCoopers, the lead advisor for the sale of K Shipbuilding, have begun working-level procedures to sign an MOU designating Hankuk Carbon and Taekwang Industrial as conditional prospective buyers. An open competitive bidding process will follow the signing of the MOU, using it as the basis.
The sale covers a 99.6% stake in K Shipbuilding held by K Sunshine Holdings, a special-purpose company (SPC) of UAMCO, and KHI. The price for the existing shares is said to be in the 600 billion won range. The total transaction could reach around 900 billion won, including new share issuance and corporate bonds, according to market observers.
In the previous sale, Taekwang Group participated as the sole bidder in a consortium with Osung Advanced Materials, Green Harbor Asset Management and others, but the process ended this past June without a preferred bidder being selected. The sellers judged that, given the nature of the shipbuilding industry, a strategic investor (SI) that would take direct responsibility for the business needed to lead the bid.
The focus of interest in this sale is Hankuk Carbon. Founded in 1984, the company was the first in Korea to commercialize carbon-fiber prepreg. Its market capitalization was about 1.0594 trillion won as of the 6th, and its cash and cash equivalents on a consolidated basis stood at around 110 billion won in the first half of this year. It has a history of lending funds to K Shipbuilding in 2022 and has previously discussed collaboration on small- and medium-sized LNG tankers. If the acquisition goes through, the companies would be able to vertically integrate from materials and equipment to shipbuilding, analysts say.
The shipbuilding boom, combined with the scarcity of mid-sized shipbuilders whose management control can be acquired, has drawn attention to whether the sale will attract strong interest. Since the industry was reorganized around large shipbuilders, few mid-sized shipbuilders with stakes that could come onto the market and offer control have been available. The expansion of the eco-friendly vessel and naval vessel maintenance, repair and overhaul (MRO) markets also adds to the company’s strategic value.
K Shipbuilding’s performance has also improved. In the first half, revenue was 683.4 billion won and operating profit was 114.3 billion won, up 15% and 172%, respectively, from the same period a year earlier. Net assets stood at 609.6 billion won at the end of June, up 59% from a year earlier, while its debt-to-equity ratio fell to around 160%. Borrowings that previously depended on UAMCO’s credit support are also being repaid gradually through operating cash flow.
K Shipbuilding is competitive in its core PC tanker segment and has a strong order backlog and experience building a range of vessel types. Its location near the Jinhae District naval base, where a U.S. Navy fleet support unit is stationed, is also seen as an investment attraction, given the potential to expand into MRO work on Korean and U.S. naval vessels.
An IB industry official said, “One of K Shipbuilding’s greatest points of scarcity is that, following the restructuring of Korea’s shipbuilding industry, there are few mid-sized shipbuilders on the market whose management control can be acquired.” The official added, “This time, whether an SI capable of actually driving the shipbuilding business emerges—not just the price—will be key to completing the deal.”
[email protected] Kang Gu-gwi Reporter