[Editorial] With Production, Consumption and Investment All Declining, Revive Domestic Demand Instead of Being Optimistic
- Input
- 2026-09-30 18:38:13
- Updated
- 2026-09-30 18:38:13
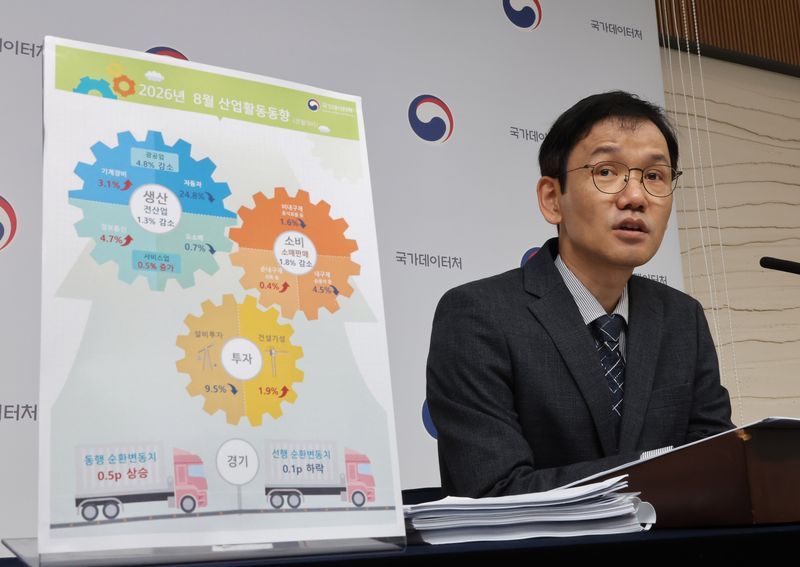
One month's figures alone do not justify concluding that the economic trend has turned downward. Special factors, including summer vacations in the auto industry and strikes at some companies, must also be taken into account. In fact, automobile production plunged 24.8%, its steepest decline since February 2020, pulling down the overall indicators. Facility investment was also significantly affected by a base effect following a sharp increase in ship and aircraft investment in July. By contrast, investment in machinery, including equipment used to manufacture semiconductors, increased, as did service-sector production. For these reasons, the government expects production, consumption and investment to rebound across the board in September.
Still, it is premature to be optimistic about an economic recovery under these circumstances. Consumption is particularly worrisome. Temporary factors, such as disruptions to automobile production and front-loaded demand for home appliances, played a role, but the two-month decline in consumption cannot be blamed solely on special factors. According to an announcement by the Ministry of Employment and Labor on the same day, real wages in July also fell 0.3% from a year earlier, marking their fourth consecutive monthly decline. Nominal wage growth is failing to keep pace with inflation. As household purchasing power weakens, consumption inevitably loses its ability to recover.
On top of this, the burden of interest rates is rising again. The average annual interest rate on bank mortgage loans stood at 4.66% in August, rising for the fourth consecutive month to its highest level in three years and nine months. The rate on unsecured credit loans jumped to 6.33%, while the rate on all household loans climbed to 4.76%. In other words, household incomes are failing to keep up with prices while the burden of loan interest is increasing. This is hardly a favorable environment for consumption and investment to recover on their own.
External conditions are also challenging. Long-term U.S. Treasury yields remain high at around 5%, fueling concerns that high interest rates will persist for an extended period. High rates in the United States also put upward pressure on domestic market interest rates and the exchange rate. Economic policy must now be managed on the assumption that interest rates may remain elevated for some time.
The more difficult the situation becomes, the less the government should rely on short-term stimulus measures that use fiscal spending to artificially boost consumption. Responding to an economic slowdown by increasing bond issuance could create a vicious cycle by pushing market interest rates even higher. Limited fiscal resources should be focused on vulnerable groups and future growth engines, while unnecessary and nonurgent regular spending should be curtailed as much as possible.
As has been repeatedly pointed out, investment must not depend solely on booms in a few industries, such as semiconductors. Sweeping improvements to regulations and licensing procedures are needed so companies can spend on new factories and equipment. Obstacles to investment at industrial sites must be removed decisively. If high interest rates persist for an extended period, the risk of insolvency will rise again among vulnerable borrowers, marginal companies and real estate project financing (PF) projects. Authorities should carry out preemptive restructuring before problems worsen and strengthen the financial sector's loss-absorbing capacity.
There is no need to exaggerate August's 'triple decline' as a sign of recession. But it is clearly not a situation in which the country can be optimistic about an economic recovery simply because temporary factors were involved. Even if September's indicators rebound as expected, what matters is not a one-month rebound but the sustainability, strength and breadth of the recovery. The government must address, one by one, the vulnerabilities in domestic demand, including falling real wages, households' interest burdens and weakening corporate investment, while building economic resilience capable of withstanding a prolonged period of high interest rates. Ensuring that the warmth generated by semiconductors and exports spreads to consumption and investment is the top policy priority now.