"A-Rated but Priced Like BBB"... Samcheok Blue Power and LOTTE Engineering & Construction Show a Credit Rating 'Gap' [fn Market Watch]
- Input
- 2026-09-29 14:10:00
- Updated
- 2026-09-29 14:10:00
[Financial News] The gap between credit ratings and bond prices is becoming increasingly pronounced in the bond market. Even companies rated A by credit rating agencies are being priced in the secondary market with risk premiums equivalent to those of BBB-rated bonds, showing that investors are taking a more conservative view than the official ratings suggest.
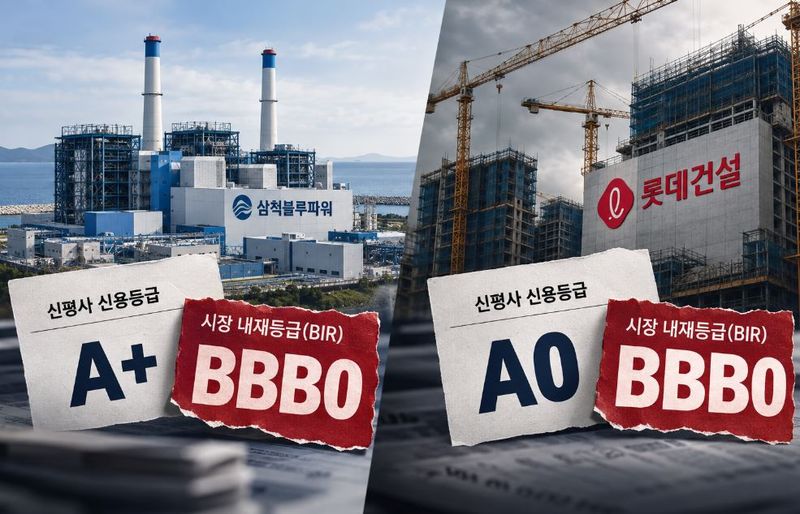
According to private assessments by bond valuation firms as of the 28th, Samcheok Blue Power's official credit rating was A+, while its market-implied rating (BIR) was BBB0, four notches lower. BIR is an indicator that converts yields calculated from bond prices formed in the secondary market into credit ratings. In effect, it allows comparisons between the rating table assigned by credit rating agencies and the rating table assessed by the market through prices.
Samcheok Blue Power's market-assessed yield on its three-year bonds was 7.457%, with the spread over the rate implied by its rating at around 230bp (1bp = 0.01 percentage point).
The rating spread widened as maturities lengthened, from 135bp for one-year bonds to 164.5bp for two-year bonds and 230bp for three-year bonds. This means the market is applying a higher risk premium to longer-term bonds.
There is also a significant price gap among bonds with the same A+ rating. POSCO E&C's market-assessed yield on three-year bonds was 5.367%, with a rating spread of 21bp. The difference in spreads compared with Samcheok Blue Power reached 209bp. Although their official credit ratings are identical, bond prices in the secondary market are diverging widely based on factors such as each company's business risks, supply and demand, and liquidity.
This is the result of institutional investors increasingly shunning the companies.
A financial investment industry official said, "Coal-fired power plants will be off-limits for investment from 2030, but in reality, many institutional investors, including the National Pension Service (NPS), have already refrained from investing in them."
The growing calls from civic groups urging the bond market to uphold environmental, social and governance (ESG) values are also believed to have contributed.
Korea Beyond Coal, a coalition of 24 civic groups including Solutions for Our Climate (SFOC) and Green Korea United, is conducting a joint campaign to phase out coal. The groups delivered letters to securities firms asking them to stop underwriting corporate bonds and called on them to halt decision-making that runs counter to the climate crisis.
LOTTE Engineering & Construction's official credit rating is A0, but its BIR is BBB0, three notches lower. Its market-assessed yield on three-year bonds was 7.082%, with a rating spread of 165bp.
A high risk premium is also evident in the short-term funding market. LOTTE Engineering & Construction's commercial paper (CP) yields were 5.120% for one-month maturities and 5.270% for three-month maturities, with spreads over the rates implied by its rating of 163bp and 164bp, respectively. These levels are similar to the 165bp rating spread on its three-year corporate bonds.
However, CP and corporate bonds differ in maturity, product characteristics and liquidity, limiting the validity of a simple comparison. Nevertheless, the fact that short-term instruments carry additional yields similar to those on three-year corporate bonds indicates that the risk premium on LOTTE Engineering & Construction is elevated across the maturity spectrum.
Meanwhile, bond market participants say the gap between official ratings and market prices warrants attention if it persists for an extended period. It signals that investors are continuing to demand a high risk premium from the company, regardless of whether credit rating agencies adjust its rating.
A bond market official observed, "Credit ratings move through a set evaluation process, but investor judgments are immediately reflected in bond prices. For companies where the gap persists, it is necessary to examine why the market is demanding additional yield."
[email protected] Kim Hyun-jung Reporter