She Had an Ownership Share, Yet Not a Word Was Said... Calls Grow to Improve the 'Loans Secured by Jointly Owned Property' System
- Input
- 2026-09-23 16:24:25
- Updated
- 2026-09-23 16:24:25
[Financial News]#. A, who had built a family and household with his wife over 16 years, learned only later that his wife, B, had secretly borrowed a large sum from a lending company using her share of a jointly owned home as collateral. B took out the loan without A's knowledge, even though A had neither consented to the loan nor provided his seal.B had actually borrowed approximately 250 million won. The maximum amount secured by the mortgage was set at 450 million won. When the debt was not repaid, the lending company put the property up for a foreclosure auction.A, who had not personally borrowed the money, was nevertheless affected by the property interests tied to the jointly owned home. The two later began divorce proceedings, and A did not receive a sufficient explanation or apology from B regarding the loan or the resulting property issues. Their close-knit 16-year marriage was shattered in an instant, largely because of B's excessive extravagance.The case revealed that verification procedures for loans secured by jointly owned property vary among financial institutions, potentially creating a blind spot in which a non-debtor co-owner learns of the situation only after the fact.
Banks and Savings Banks Say "Co-Owners Must Be Verified"; Lending Companies Say "Loans Secured by Ownership Shares Are Available"
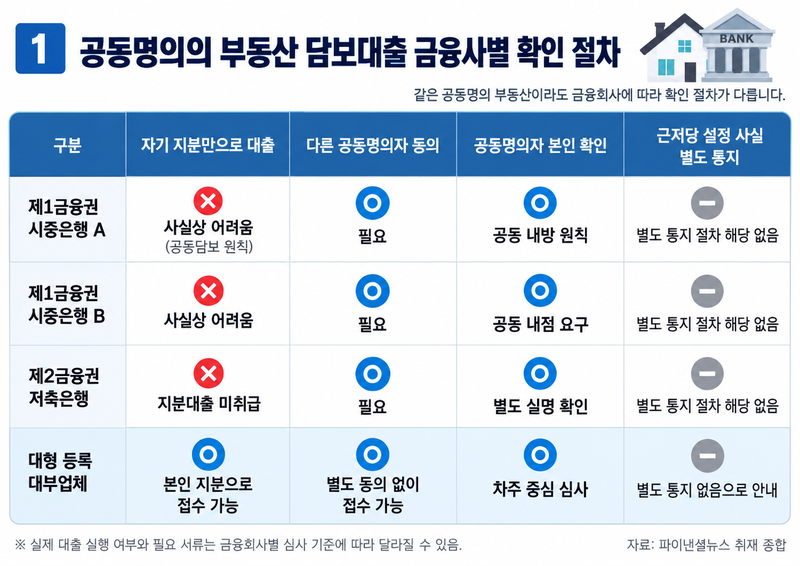
According to Financial News' reporting on the 23rd, two commercial banks said it was difficult to process a loan secured by jointly owned property without the participation of the other co-owner.
One commercial bank explained, "If the property is jointly owned, all co-owners must come to the branch together to proceed." Another commercial bank likewise said, "If it is jointly owned, both of you must come," requiring all co-owners to visit in person.
A savings bank in the nonbank financial sector also required the other co-owner's consent and identity verification. The savings bank explained, "We do not offer loans secured by an ownership share," adding, "Both parties must consent."
By contrast, a lending company said it was possible to apply for a loan secured solely by the applicant's ownership share. A representative of the company said, "There is something called a loan secured by an ownership share," and added, "A loan equivalent to the customer's ownership share is also possible." When asked whether the company directly notified the other co-owner of the loan by phone or text message, the representative replied, "No, we do not do that."
The lending company was a large registered lender subject to the oversight and supervision of the Financial Services Commission (FSC) and the Financial Supervisory Service. According to the registered lending industry, cases of damage similar to A's are known to number only a few per year on average. The Financial Supervisory Service also has no compiled data on similar cases. However, concerns are growing that similar cases could gradually increase, prompting calls for institutional improvements and other measures to prevent such harm.
Under the current Civil Act, it is not inherently impossible for one co-owner to take out a loan using his or her own ownership share as collateral. Article 263 of the Civil Act allows a co-owner to dispose of his or her share. The consent of the other co-owners is required to dispose of or alter the entire jointly owned property, but consent is not required when only one's own share is offered as collateral.
A Need for Means to Recognize Changes in Property Interests
The issue is awareness rather than consent. One co-owner may use his or her own share as collateral, but there is no common mechanism requiring the other co-owner to be notified when a mortgage is created over that share and the legal status of the jointly owned property changes. A non-debtor co-owner may therefore learn only later that a security interest has been placed on property he or she owns jointly with someone else.
This is why legal experts point out that, without a separate notification procedure, the other party may realize that his or her property interests have changed only after the borrower's debt becomes delinquent or foreclosure proceedings begin.
Creating a security interest over one co-owner's share is different from disposing of the other co-owner's share itself. Even so, it can have a real impact on the other co-owner because it complicates the rights associated with the jointly owned property and may lead to subsequent procedures, such as a foreclosure auction, if the debt remains unpaid. Legal experts say that this is particularly serious when the property is held as a residence, since a non-debtor co-owner's living arrangements and property interests could be destabilized by a problem unrelated to his or her own debt.
Another factor widening this blind spot is the lack of standardized verification procedures among financial institutions. Some financial companies have their own procedures requiring a co-owner's consent or identity verification, but no standard or supervisory rule requiring them to be applied uniformly across the financial sector has been identified.
Legal experts believe a realistic alternative would be to establish at least a basic procedure for notifying other co-owners when an important change in rights, such as the creation of a mortgage, occurs, rather than restricting a co-owner's right to dispose of his or her own share. The idea is that simple notification would allow a non-debtor co-owner to identify the situation early and respond without infringing on the co-owner's right of disposition.
There is currently no unified mechanism at the level of the financial authorities. An FSC official explained, "As I understand it, the banking supervision regulations do not require this," indicating that issues involving ownership shares are more closely related to property relations under civil law.
Accordingly, legal experts say institutional improvements are needed, including the establishment of minimum notification standards.
A real estate attorney said, "Even if the specific method is left to the discretion of each financial company, it would be advisable to require a procedure for confirming the parties' intentions," adding, "Including a verification procedure in the operational manual could help prevent harm."
Another real estate attorney also predicted, "Even if a co-owner secretly takes out a mortgage loan on the home, a system requiring both parties to be notified is necessary," adding, "Without such a system, cases of abuse will gradually increase."
[email protected] Yoo Seon-jun Reporter