Online investment-linked finance restrictions to be eased: "Easier access to loans for mid- and low-credit borrowers"
- Input
- 2026-09-22 11:26:07
- Updated
- 2026-09-22 11:26:07
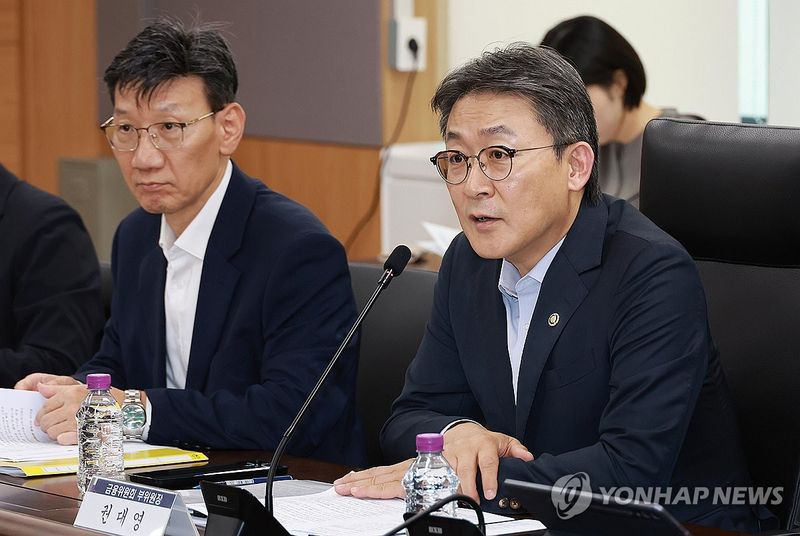
On the 22nd, FSC Vice Chairman Kwon Dae-young chaired a meeting with the online investment-linked finance industry at Front1 in Mapo, Seoul. The FSC announced three strategies and eight tasks to help the sector restore its intended role in the mid-interest-rate lending market.
As of August 2026, cumulative lending by the online investment-linked finance industry had surpassed 20 trillion won. Personal credit loans through savings bank-linked investments also exceeded 500 billion won, demonstrating continued growth. However, real estate-collateralized loans and stock-backed loans account for about 70% of the market, indicating that its collateral concentration persists. Credit loans have remained at an average of 11.6% over the past five years. In particular, as of the end of last year, loans to borrowers with mid- and low-credit ratings accounted for 63.1% of the sector's lending, significantly below the figures for savings banks (99.7%), insurance companies (95.3%), and credit-specialized finance companies (99.6%).
Some online investment-linked finance operators have even resorted to business practices that circumvent advertising regulations. Because management indicators are not sufficiently verified and the market has not yet fully developed, it is taking time to remove insolvent companies from the market. The FSC prepared a plan to promote funding for borrowers with mid- and low-credit ratings, aiming to improve business practices in the sector and strengthen its role as an alternative finance market for financially underserved groups.
First, the FSC will introduce a system recognizing "outstanding online investment-linked finance operators for mid- and low-credit borrowers." Operators with strong records in lending to such borrowers, credit assessment capabilities, and financial soundness will receive incentives, including more favorable investment limits and methods. For example, incentives will be available to operators that have a three-year record of personal and individual business-owner credit lending; a share of at least 60% or an outstanding balance of at least 30 billion won in loans to borrowers with mid- and low-credit ratings; their own alternative credit assessment model and personnel; personal credit loan interest rates of 15% or less; equity capital of at least 1 billion won; and a delinquency rate below 5%, among other requirements.
The incentives are intended to make it somewhat easier to raise funds. For example, the investment limit for an operator's own funds will be raised from 20% to 40% of the amount raised, while the limit for financial company-linked investments will increase from 40% to 50%. The measures also include allowing small-scale diversified investments, separately managing investment funds and repayment funds, specifying investment terms, and requiring portfolios to contain at least 70% loans to borrowers with mid- and low-credit ratings. These conditions are intended to strengthen investor protection and choice.
The investment limit for general investors will be raised from 40 million won to 50 million won. The institutions and loan categories eligible for financial company-linked investments will also be expanded. Participation will be broadened beyond savings banks to mutual finance cooperatives, while eligible investments will expand from personal credit loans to individual business-owner credit loans.
Infrastructure will also be improved to make borrowing more convenient for people with mid- and low-credit ratings. The Central Record Management Institution's system will be upgraded so that when a borrower requests an extension of maturity, the maturity can be extended using the existing investment funds without fully repaying the existing loan. A new function will allow operators to raise only the amount involved when part of an investment is recovered. System integration will also be pursued to enable online investment-linked finance operators to use a small-business-specialized credit assessment model (SCB) to expand credit loans for individual business owners.
The FSC will introduce external audits of key management information, including delinquency rates on linked loan receivables and sales of nonperforming loans, while expanding the disclosure of loss rates. These measures are designed to improve credibility. To prevent distortions in delinquency-rate information, a legal basis will also be established for terminating linked loan and investment contracts, with the consent of a specified percentage or more of investors, when no additional recovery of the receivables is possible. The Online Investment-Linked Finance Association plans to strengthen its self-regulatory functions by establishing a system for prior review and follow-up measures concerning unsound advertising, as well as guidelines for managing long-overdue receivables.
A system for the smooth closure and wind-down of online investment-linked finance operators will also be established. To facilitate the exit of insolvent operators from the market, a legal basis for the ex officio cancellation of registration will be created. Even after registration is canceled or revoked, an operator will retain its status within the scope necessary to conclude linked loan and investment contracts, and user-protection obligations will continue to apply. When a business closes, investor-protection measures—including advance notice to users, operation of a complaint-handling channel, and destruction of credit information—will be mandatory. Rights derived from linked loan receivables, such as collateral and proceeds from the sale of receivables, will be explicitly recognized as investor property and afforded the same safeguards.
The FSC plans to accept and review applications for innovative financial services by the first quarter of 2027, including the introduction of the outstanding-operator system for loans to borrowers with mid- and low-credit ratings and the expansion of financial company-linked investments. It also plans to complete by the first quarter of 2027 measures requiring legislative or regulatory amendments, including the creation of a maturity-extension system, integration with a credit assessment system for small businesses, and improvements to closure procedures.
[email protected] Park Moon-soo Reporter