HYBE's Earnings Are Strong, but Target Price Cut... "BTS Is Key"
- Input
- 2026-09-22 08:46:56
- Updated
- 2026-09-22 08:46:56
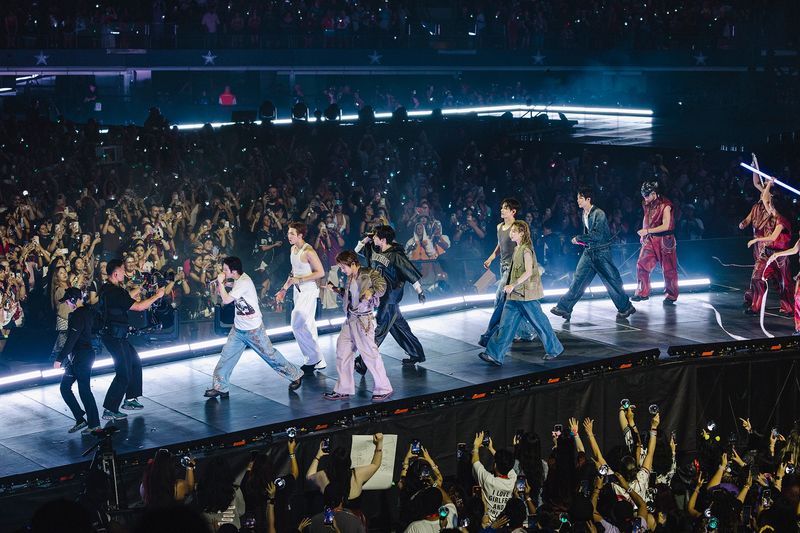
[Financial News] SK Securities said reducing HYBE's reliance on BTS is key and that securing younger intellectual properties (IPs) will be crucial going forward. It maintained its "Buy" rating on the company but cut its target price from KRW 350,000 to KRW 290,000 to reflect the recent decline in industry valuations.
Park Jun-hyung, a researcher at SK Securities, said, "HYBE's revenue this year is projected to reach KRW 5.1 trillion, while operating profit is expected to come to KRW 301.8 billion. That would represent year-on-year increases of 93.2% and 504.9%, respectively, exceeding market consensus estimates."
The analysis attributed this year's performance to the combined impact of BTS resuming activities after completing their military service and contributions from younger IPs such as CORTIS and KATSEYE.
In the medium to long term, growth in new and younger IPs will be key, analysts noted. However, securing new IPs is also expected to be supported by mega IPs.
Park explained, "With securing new IPs essential, the solution also comes from owning mega IPs. When organizing global tours, agencies with artists on the level of BTS gain an advantage in local negotiations. This network is being transferred directly to younger artists."
He forecast a positive outlook for next year amid this trend. Park said, "Revenue next year is projected at KRW 4.6 trillion, down 9.8% from the previous year, while operating profit is expected to rise 63.78% to KRW 494.3 billion. The operating margin is also projected to improve from 5.9% to 10.7%. Despite the contraction in scale, we believe this marks a period in which improved earnings quality is becoming evident, as profitability is increasing."
[email protected] Lim Sang-hyuk Reporter