"My Parents Told Me Never to Buy Stocks"—I Mocked Them for Being Out of Touch, but Now Young Retail Investors Are Losing Sleep [World of Retail Investors]
- Input
- 2026-09-20 06:00:00
- Updated
- 2026-09-20 06:00:00
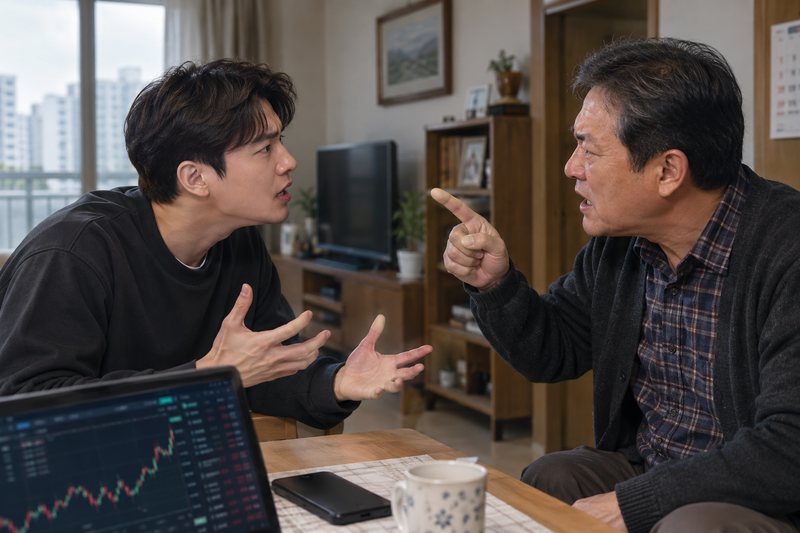
[Financial News] #. A, 29, a recent entrant to the workforce, had a heated argument with his parents early this year. The KOSPI Composite Index was surging day after day. His father became upset after seeing A constantly checking his stock-trading app, saying, "Don't ever invest in stocks. It's gambling." A retorted, "What era are we living in? My father's thinking is so outdated."However, in less than six months, Ahis father's reproachful stare whenever stock-market news came outHe complained that he was receiving it. The KOSPI Composite Index began a steep decline after hitting an all-time closing high of 9114.55 on June 22. When he heard that the drop had surpassed those seen during the 1997 Asian financial crisis and the 2008 global financial crisis, A stopped checking his account. His account had already fallen more than 30% from its peak, and he could not help but recall his father's words: "Stocks are gambling. Don't invest in them."
Why people in their 50s and 60s say stocks are gambling: They learned the hard way
Many people in their 50s and 60s are wary of stocks, saying they are gambling, becausethey have a history of experiencing the stock market's painful side firsthandis the reason.
The KOSPI Composite Index stood at just 164 points at the end of 1985, but rode the three-lows boom—low interest rates, a low dollar and low oil prices—to break above 1000 points for the first time in March 1989. It rose nearly sixfold in about four years, sparking a stock-investment boom amid rosy expectations based on the real economy. Indiscriminate investing became widespread, and the record-setting bull market continued. This was when today's people in their 50s and 60s were just entering society.
The index then entered a prolonged decline, and the IMF financial crisis erupted in 1997. After taking a decisive blow, the KOSPI Composite Index plunged to 277.37 by June of the following year. Stories of breadwinners who invested and lost their entire fortunes, as well as people who borrowed money to invest and ended up losing their homes, became part of that generation's collective memory. Andfor roughly 16 years from 1989 through 2005, the KOSPI Composite Index hovered around the 1000-point leveland fluctuated within a narrow range, ushering in a long era of the "range-bound KOSPI."
Moreover, there was little reason to invest in stocks back then. According to data from the Bank of Korea (BOK)'s Economic Statistics Department, the average interest rate on time deposits at commercial banks was 10% in 1992. Commercial bank rates averaged 23% in the 1970s and 14% in the 1980s—high-interest-rate levels incomparable to those today.
In fact, broadcaster Song Eun-i made headlines after it became known that she still maintains a high-interest savings account opened in the 1990s. Song Eun-i later explained on her YouTube channel, VIVO TV, "I opened a bank pension savings account in 1993, when I was earning a monthly salary of 200,000 won. The interest rate was in the 20% range at the time. The bank recommended several times that I close the account, but I have kept it until now," adding, "I opened it for the tax benefits and to receive a pension, so the amount is not large."
The reality for people in their 20s and 30s in 2026 is different
The problem is that the world inhabited by today's people in their 20s and 30s is completely different from the one their parents knew. According to the Korean Statistical Information Service (KOSIS) this July, last yearthe homeownership rate among people in their 20s and 30s fell into the 20% range for the first time since statistics under the current system began. At the same time,the asset gap with people in their 50s and 60s reached its widest level ever, making real estate an asset that people cannot afford even if they want to buy it.
According to the Ministry of Land, Infrastructure and Transport (MOLIT), the median price-to-income ratio (PIR) for owner-occupied households in Seoul was 13.9 times last year. The PIR is an indicator of how long it would take to buy a home if one saved an entire salary,meaning that people in Seoul must save their entire salary for roughly 14 years to buy a home.
Unlike their parents' generation, people in their 20s and 30s now face a situation in which buying a home is virtually impossible on a salary alone. Bank deposit rates have also remained far lower than those enjoyed by their parents' generation, while the prices of major assets, including real estate, have risen sharply day after day. Some analysts say stock investing is therefore being viewed as virtually the only "ladder for building wealth."For people in their 20s and 30s, stocks are not a choice but a means of survivalThat is the reality.
However, if investors focus only on short-term returns, stocks ultimately become gambling, just as A's father said. Experts therefore agree that investors should avoid gambling-like short-term trading and high-risk products pursued in the hope of making large profits quickly.John Lee, former CEO of Meritz Asset Management, recently said on a YouTube channel, "The path to becoming wealthy is never quick; you have to invest in time,""Checking your phone all day after buying roughly 100 shares is gambling, not investing"he also emphasizedon one occasion.
I don't want to become one of the "should-have" crowd, but today I ended up saying again, "I should have bought, I should have sold, I should have held..."Stocks, real estate and personal finance all seem to be going well for everyone except me. The world of investing is difficult no matter how much I study. To conveniently receive[World of Retail Investors]—a series readers can applaud and relate to—please subscribe to the reporter's page.
[email protected] Kim Hee-sun Reporter