S-Oil Corporation Target Price Raised to KRW 220,000 as Refining Margins Remain Strong—Shinhan Investment & Securities
- Input
- 2026-09-17 05:59:00
- Updated
- 2026-09-17 05:59:00
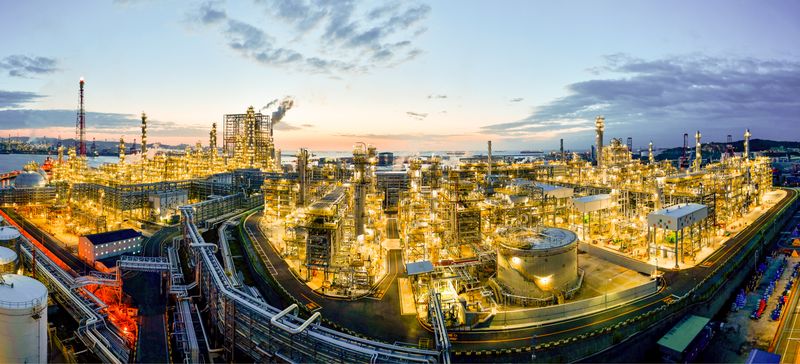
[Financial News] International oil prices have risen again due to supply disruptions originating in the Middle East. However, analysts expect S-Oil Corporation’s earnings improvement to continue as refining capacity remains limited and petroleum-product inventories stay low. Shinhan Investment & Securities raised its forecast for S-Oil Corporation’s operating profit this year by 5.4% to KRW 5.2327 trillion and lifted its target price from KRW 200,000 to KRW 220,000.
On the 17th, Shinhan Investment & Securities maintained its “Buy” rating on S-Oil Corporation and raised its target price by 10% to KRW 220,000.
Lee Jin-myeong, a senior researcher at Shinhan Investment & Securities, cited the difficulty of replacing refining capacity in the short term as an investment rationale, even as crude oil supply routes from the Middle East remain unstable.
Shinhan Investment & Securities forecast S-Oil Corporation’s revenue this year at KRW 43.5774 trillion and operating profit at KRW 5.2327 trillion. These figures represent increases of 3.0% and 5.4%, respectively, from its previous forecasts. Its forecasts for next year’s revenue and operating profit were also raised by 7.0% and 3.1%, respectively, to KRW 41.6243 trillion and KRW 3.7995 trillion. The estimated operating margin for this year is 12.0%.
Refining margins are the key basis for the upgraded earnings forecast. According to the report, the complex refining margin reached $34 per barrel in August, or 4.8 times its historical average. The diesel margin was particularly strong, at 4.3 times its historical average, compared with 2.1 times for gasoline. In its August report, the International Energy Agency (IEA) also analyzed that refining margins remained high as middle-distillate markets, including diesel and jet fuel, tightened due to disruptions to petroleum-product exports from the Middle East and attacks on Russian refining facilities.
The report also found that conditions remain favorable in terms of crude procurement costs. Saudi Aramco’s official selling price (OSP) for Arabian Light crude bound for Asia fell from a premium of $19.5 per barrel over the average Oman-Dubai crude price in May to a discount of $2 per barrel in both September and October.
However, disruptions to Middle Eastern crude shipments remain a variable. After the suspension of Saudi Arabia’s East-West Pipeline disrupted alternative exports through Yanbu Port on the Red Sea, Saudi Aramco has sought to diversify supply routes to Asia by using transshipment near Sohar, Oman. As a result, even if crude price terms remain low, the timing and volume of actual deliveries could become more volatile.
Shinhan Investment & Securities also viewed low petroleum-product inventories as a factor supporting strong refining margins. According to the U.S. Energy Information Administration (EIA), U.S. middle-distillate inventories fell to around 104 million barrels in late August. The IEA likewise analyzed that global oil inventories declined rapidly following supply disruptions in the Middle East.
The fact that the investment expansion cycle is passing its peak was also cited as a basis for greater dividend capacity. Shinhan Investment & Securities expects S-Oil Corporation’s capital expenditures to fall by approximately 76%, from KRW 2.1 trillion this year to KRW 500 billion next year. Accordingly, it estimated the dividend yield at 4.6% this year and 6.1% next year. The Shaheen Project is targeting commercial operations early next year after trial operations during the second half of this year.
[email protected] Kim Mi-hee Reporter