"Samsung SDI, 4-Year Discount Finally Ends"... SK Innovation, Target Price Raised on Triple Positive News from Oil Refining [Stock Topia]
- Input
- 2026-09-15 10:58:56
- Updated
- 2026-09-15 10:58:56
[Financial News] Here is a summary of reports from major securities firms for the morning of September 15.
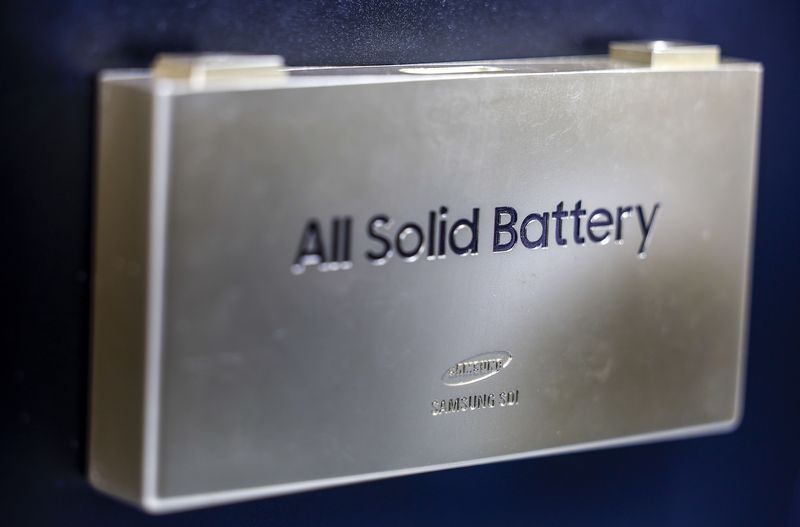
Samsung SDI received an evaluation that the discount it had received over LG Energy Solution for the past four years has been resolved, driven by a preference for prismatic and cylindrical batteries and expanded orders for energy storage systems (ESS).
Analysis suggests that SK Innovation will see a windfall in earnings this year that is much greater than expected, driven by a super-boom in the oil refining and lubricants sectors compounded by geopolitical variables such as the war with Iran. Battery materials maker POSCO Future M was named the top pick among the three domestic materials companies, based on additional orders for lithium iron phosphate (LFP) cathode materials and the indirect benefits from China's export restrictions on anode materials.
Samsung SDI Revalued by ESS Performance (NH Investment & Securities)
◆ Samsung SDI (006400)― NH Investment & Securities / Researcher Ju Min-woo- Target Price: 730,000 KRW (Upward by 21.7%, from 600,000 KRW) | Previous Day's Closing Price: 532,000 KRW
- Investment Opinion: Buy (Maintain)
NH Investment & Securities raised its target price for Samsung SDI to 730,000 won, stating that the company is breaking free from the discount it has received compared to LG Energy Solution over the past four years. The firm raised its ESS earnings forecast to reflect increased visibility regarding orders from China's Sungrow, projecting that ESS operating profit will grow from 51 billion won last year to 968 billion won this year and 1.603 trillion won next year.
The analyst suggested early 2027 as the next time for re-evaluation, anticipating the confirmation of Europe's Industrial Acceleration Act (IAA) and additional orders for electric vehicles (EVs). "The reasons for the re-rating are the strengthened competitiveness in securing orders due to the preference for prismatic and cylindrical shapes, and the ability to respond promptly to demand by leveraging equity in affiliates," the analyst stated. "Further re-rating is possible if additional EV orders are secured following the confirmation of the IAA in early 2027."
They viewed the fact that it possesses the battery form factor desired by customers and has the investment capital in the form of a stake in Samsung Display as a structural strength, enabling it to respond immediately when demand arises.
Operating profit for the third quarter is projected to reach 260.3 billion won, more than double the market expectation of 107 billion won. However, it was noted that the impact is significant due to a one-time effect reflecting approximately 150 billion won in liquidation compensation for the GM joint venture, and that sales of electric vehicle batteries are slowing due to inventory adjustments of older BMW models.※ Energy Storage System (ESS)It is a device that stores electricity in large batteries and releases it when needed. Demand is rapidly increasing as it evenly supplies electricity with fluctuating outputs, such as solar and wind power, and is also used as an emergency power source for data centers that consume large amounts of electricity.※ Rectangular and cylindrical batteriesThis classification is based on the external shape of the battery housing. Prismatic types are contained in square metal cans, while cylindrical types are housed in round cans similar to dry batteries; these forms are sturdier than thin pouch types and are advantageous for mass production. Samsung SDI focuses on these two forms as its main products.
SK Innovation, Stock Price Cheap Compared to 10 Trillion Won Operating Profit (Yuanta Securities)
◆ SK Innovation (096770)― Yuanta Securities / Researcher Hwang Kyu-won- Target Price: 200,000 KRW (Upward by 17.6%, from 170,000 KRW) | Previous Day's Closing Price: 136,700 KRW
- Investment Opinion: Buy (Maintain)
Yuanta Securities raised its target price for SK Innovation to 200,000 won, stating that the extent of earnings improvement will be greater than initially expected as the refining and lubricants businesses benefit from rising international oil prices and supply disruptions. It also projected that this year's operating profit could reach 10 trillion won, an estimate based on the assumption that geopolitical variables, such as the prolonged war with Iran, will persist.
Researcher Hwang predicted that "earnings windfalls in 2026 will be much greater than expected due to the 'triple tsunami effect' surrounding the oil refining industry." He explained that the global supply and demand of petroleum products has tightened by about 14% due to a combination of crude oil supply disruptions caused by the war in Iran, damage to petrochemical facilities in the Middle East and delays in restarting operations, and damage to energy facilities caused by the war between Russia and Ukraine.
However, it was assessed that the remaining restructuring must be completed to increase corporate value. These include the merger of SK IETechnology, the sale of city gas subsidiary SK City Gas Holdings to KKR, and the possibility of suspending operations at SK GeoCentric's naphtha cracking facility (NCC) in 2027. Analyst Hwang analyzed that "the performance effect from the refining and lubricants sectors will be greater than the decrease in corporate value resulting from the restructuring."※ Naphtha Cracking Center (NCC)It is a petrochemical facility that breaks down naphtha extracted from crude oil at high temperatures to produce ethylene, which serves as a raw material for plastics and synthetic fibers. As the price of general-purpose products has fallen due to China's recent large-scale expansion, government-led restructuring is underway to reduce facilities in areas such as Ulsan.
POSCO Future M Benefits from Anode Material Shortage (Daol Investment & Securities)
◆ POSCO Future M (003670)― Daol Investment & Securities / Researcher Yoo Ji-woong- Target Price: 290,000 KRW (Maintain) | Previous Day's Closing Price: 178,900 KRW
- Investment Opinion: Buy (Maintain)
Daol Investment & Securities maintained a target price of 290,000 won for POSCO Future M, stating that the company is a key player in resolving lithium iron phosphate (LFP) supply chain bottlenecks and that its position is emerging within a non-FEOC supply chain that avoids U.S. Foreign Economic Concern Agency (FEOC) regulations.
Although operating profit for the third quarter was projected to be 24.5 billion won, a 55% decrease from the previous year, attention was paid to the fact that the volume of cathode materials to Samsung SDI is normalizing.
"Researcher Yoo stated, 'With the recent completion of the line conversion from ternary to LFP, additional orders are expected, and valuation burdens are anticipated to be sufficiently overcome through structural benefits resulting from China's export restrictions on cathode materials in November,' adding, 'I recommend it as the top pick among the three major domestic materials companies.'" The analysis suggests that entry into the LFP cathode material market has begun in earnest as battery cell manufacturers shift their North American factories from electric vehicles to ESS.
In particular, it was anticipated that there would be significant indirect benefits for cathode materials. POSCO Future M plans to increase its domestic cathode material production capacity from 13,000 tons to approximately 70,000 tons by 2029–2030 through expansion in Vietnam.
Researcher Yu stated, "In the mid-to-long term, based on the 250 GWh share of Non-FEOC compliance within North America's 400 GWh battery production capacity, the potential market size for non-Chinese anode material manufacturers reaches 250,000 tons," adding, "A severe anode material shortage could persist starting from the end of this year."※ Lithium Iron Phosphate (LFP)It is a type of battery cathode material that is cheaper and more fire-resistant than ternary materials using nickel and cobalt, but has lower energy density. It is mainly used in entry-level electric vehicles and ESS, and Chinese companies have almost monopolized the market until now.※ Cathode materialAs a core material on the lithium-ion release side of the battery, it effectively determines the battery's capacity and output. It accounts for the largest share of the battery's cost and is broadly divided into ternary compounds, which are a mixture of nickel, cobalt, and manganese, and the cheaper lithium iron phosphate (LFP).※ Cathode materialIt is a core battery material that receives and stores lithium ions during charging and releases them during discharge. It is primarily made from graphite, and China accounts for the majority of the global supply. With the U.S. refusing to subsidize batteries containing Chinese materials and China threatening export restrictions, the value of these materials is rising as companies capable of mass-producing cathode materials outside of China are scarce.Foreign Entity of Concern (FEOC)This refers to companies related to specific countries, such as China, that the U.S. excludes from electric vehicle subsidy eligibility. Since only batteries manufactured in supply chains compliant with this regulation (Non-FEOC) are eligible for subsidies, this is the reason behind the rising value of non-Chinese material suppliers.
[Stock Topia][Zootopia] is an AI-based stock report briefing content that collects and delivers reports from major domestic securities firms. Please subscribe to the reporter page to continue receiving [Zootopia].
[email protected] Seong Min-seo Reporter