Alteogen Now Poised for Earnings Growth After $3.2 Billion Deal; DB HiTek Undervalued Amid Exploding Chinese AI and Robotics Demand [Stocktopia]
- Input
- 2026-09-08 11:12:08
- Updated
- 2026-09-08 11:12:08
[Financial News] Here is a roundup of reports from major securities firms as of the morning of September 8.
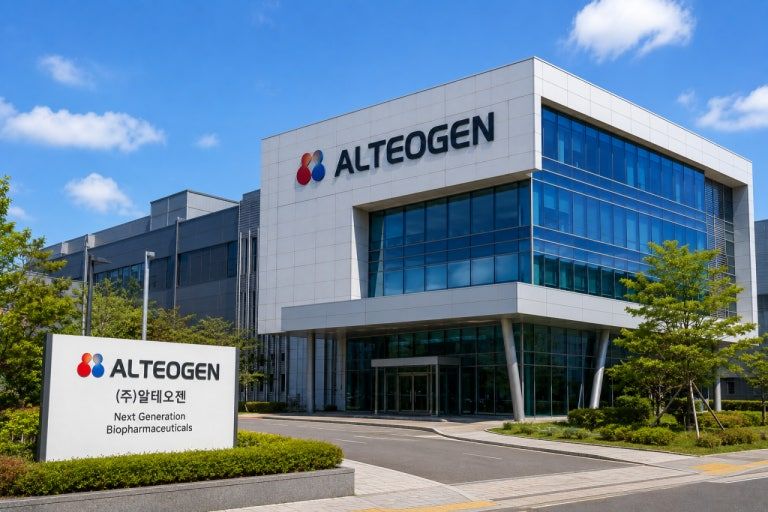
Analysts expect Alteogen to continue its earnings growth through the fourth quarter as upfront payments and milestones flow in during the second half of the year, following its technology-transfer agreement worth about 4 trillion won with Novartis.
DB HiTek is expected to exceed market expectations in the third quarter amid surging demand for Chinese artificial intelligence (AI) data centers and robots, supported by successive price increases and full factory utilization. Lotte Shopping is expected to see slightly slower department-store growth in the third quarter, but discount-store profits are projected to make up for it. Analysts also expect more positive factors for its department-store business to emerge toward year-end.
Why Alteogen’s Stock Has Remained Quiet Despite a Major 4-Trillion-Won Deal (Hana Securities)
◆ Alteogen (196170)— Hana Securities / Researcher Seona Kim- Target price: 450,000 won (maintained; recalculated from 580,000 won to reflect the bonus issue, with the company’s value unchanged) | Previous closing price: 286,000 won
- Investment opinion: Buy (maintained)
Hana Securities set a target price of 450,000 won for Alteogen, saying earnings growth is expected to continue through the fourth quarter following its $3.233 billion technology-transfer agreement with Novartis, signed on September 2, equivalent to approximately 4.4165 trillion won.
Seona Kim said, "The reason the stock did not rise significantly despite the major deal worth about 4.4 trillion won is that, considering the administration methods of Novartis’s major blockbuster products, most of the 10 to 11 items are likely to be pipelines still in clinical development. If so, it is difficult to expect the speed of cash inflows and the level of risk to be comparable to Keytruda and Imfinzi."
She nevertheless noted, "Novartis has numerous late-stage clinical pipelines involving antibodies, antibody-drug conjugates (ADCs), and antibody-oligonucleotide conjugates (AOCs), making it highly likely to exercise at least one option each year." She added that this could have a positive impact on the stock over the medium to long term.
Kim said, "As expectations for high interest rates and a liquidity-driven market have faded, the biotech sector is increasingly focused on the actual speed and timing of cash inflows." She added, "Alteogen is scheduled to receive technology-transfer upfront payments, sales milestones from KEYTRUDA QLEX, and development milestones from existing partnerships in the second half of the year, so earnings are expected to increase through the fourth quarter."※ Antibody-Oligonucleotide Conjugate (AOC)This next-generation drug-delivery platform combines an antibody that targets specific cells at a disease site with a genetic therapeutic substance called an oligonucleotide. Novartis’s del-zota, which is being developed as a treatment for muscular dystrophy, is a representative example.※ Keytruda Qlex (KEYTRUDA QLEX)This is a subcutaneous (SC) formulation of the world’s best-selling cancer drug, Keytruda, administered under the skin instead of intravenously. The key technology, which reduces an infusion lasting more than 30 minutes to a one- to two-minute injection, is Alteogen’s formulation-conversion technology ALT-B4. The product received approval from the U.S. Food and Drug Administration (FDA) in September 2025. As KEYTRUDA QLEX sales increase, Alteogen receives sales-based milestones followed by royalties.※ MilestoneIn a technology-transfer agreement, a milestone is a success payment made by a partner whenever a predetermined stage—such as entering clinical trials, obtaining approval, or reaching a certain level of sales—is completed. Unlike an upfront payment received when the agreement is signed, milestone payments are made in stages as development progresses.
DB HiTek: 8-Inch Foundry Supply-Demand Balance Reverses (KB Securities)
◆ DB HiTek (000990)— KB Securities / Researcher Lee Chang-min- Target price: 200,000 won (raised 17.6%; previous target: 170,000 won) | Previous closing price: 100,800 won
- Investment opinion: Buy (maintained)
KB Securities raised its target price for DB HiTek to 200,000 won, saying the company is expected to benefit from growth in China’s AI data-center and robotics markets. It estimated third-quarter operating profit at 120.8 billion won, up 50% from a year earlier and above market expectations.
Researcher Lee Chang-min explained, "The decline in the won-dollar exchange rate is a disappointing factor, but the impact of the first foundry price increase decided in March and the benefits of full factory utilization are now being fully reflected." He added, "The impact of the second price increase, which will begin to be reflected in this month’s earnings, will also contribute." DB HiTek exports semiconductors in dollars, so a decline in the won-dollar exchange rate puts pressure on won-denominated revenue. However, analysts believe the price increases and full utilization will offset that impact.
The key issue is the reversal in supply and demand in the 8-inch foundry market. Lee said, "In the mature 8-inch foundry market, leading companies such as Taiwan Semiconductor Manufacturing Company (TSMC) and Samsung Electronics are reducing their production capacity as they focus on 12-inch wafers, while demand has recently exploded, particularly from Chinese AI data centers and the robotics sector."
Lee added, "Despite the positive earnings trend, DB HiTek’s current 12-month forward price-to-earnings (P/E) ratio remains at about 9.4 times, so its appeal as an undervalued stock is likely to become much more prominent going forward."※ 8-Inch FoundryA foundry is a contract manufacturing business that produces semiconductors designed by other companies. Semiconductors are fabricated on round wafers. An 8-inch (200 mm) wafer is an older-generation format than a 12-inch wafer. As major manufacturers focus on advanced 12-inch processes, 8-inch production capacity has declined. However, components essential to AI servers and robots—such as power semiconductors, sensors, and analog chips—are still often made on 8-inch wafers, tightening supply.
Lotte Shopping: Discount Stores to Offset Department-Store Slowdown (KIWOOM Securities)
◆ Lotte Shopping (023530)— KIWOOM Securities / Researcher Park Sang-jun- Target price: 190,000 won (cut 9.5%; previous target: 210,000 won) | Previous closing price: 112,300 won
- Investment opinion: Buy (maintained)
KIWOOM Securities lowered its target price for Lotte Shopping to 190,000 won, expecting domestic department-store growth to slow slightly in the third quarter. It maintained its Buy rating, however, saying profits from domestic discount stores would offset the decline. Third-quarter operating profit is projected at 170.5 billion won, up 31% from a year earlier.
Researcher Park Sang-jun said, "Same-store sales growth is expected to slow slightly in the third quarter due to a reduced wealth effect following the stock-market correction and the impact of slower sales after promotional events by major home-appliance brands in June and July." He added, "However, an upward revision to domestic discount-store profit estimates will partially offset a downward revision to domestic department-store profit estimates."
Discount stores are expected to post sharply higher third-quarter same-store sales, supported by a base effect from being excluded last year from the list of retailers eligible for livelihood-recovery consumption coupons, spillover benefits from Homeplus store closures, and differences in the timing of Chuseok.
These effects are expected to diminish toward year-end, making department-store trends after November more important in the medium term. Park forecast, "Foreign-customer sales continue to grow rapidly due to spillover benefits from China’s Japan-related restrictions. In addition, consumers may bring forward purchases toward year-end ahead of bonus payments by major Korean companies in the first quarter of next year, which could lead to a sharp acceleration in department-store growth."※ China’s Japan-Related RestrictionsThis term refers to measures taken by the Chinese government that effectively target Japan, including advising Chinese citizens to refrain from traveling to or studying in Japan and restricting imports of Japanese content and seafood. As more Chinese tourists visit nearby South Korea instead of Japan, domestic department stores are benefiting indirectly.
[Stocktopia]is an AI-based stock-report briefing service that compiles and delivers reports from major Korean securities firms. To continue receiving [Stocktopia], please subscribe to the reporter’s page.
[email protected] Park Seong-min Reporter