"Hospital treatment turned 'unnecessary'"—Calls grow for urgent reform of medical-opinion brokers amid alleged manipulation in varicose-vein cases
- Input
- 2026-09-17 13:00:00
- Updated
- 2026-09-17 13:00:00
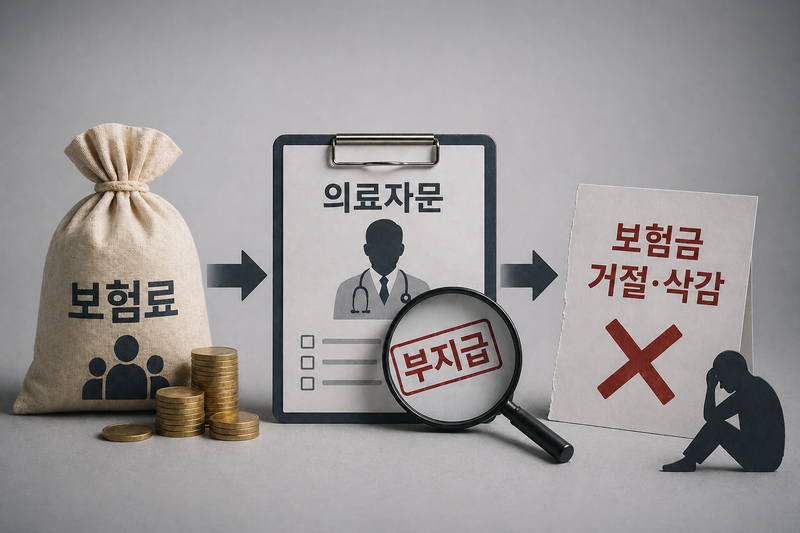
According to the insurance industry on the 17th, calls are growing to reorganize the Standard Internal Control Guidelines for Medical Opinions, established in 2021 by the Financial Supervisory Service, the Korea Life Insurance Association, and the General Insurance Association of Korea. The guidelines currently only define "medical-opinion brokerage firms" and contain no meaningful regulations governing their conduct.
However, brokerage firms rely on insurers for most of their operating funds through brokerage fees, making it difficult for them to remain free from insurers' influence. In other words, it is difficult for them to present findings that are unfavorable to insurers without alteration.
The need for revisions has gained further urgency after a recent case in which a doctor's medical opinion that inpatient treatment following surgery for varicose veins of the lower extremities was appropriate was changed, after passing through an insurer and a brokerage firm, to say that "no evidence was found that hospitalization was necessary."
Byoung Jin Min, president of the Korea Claims Adjusters Association, noted, "To prevent brokerage firms from having an incentive to manipulate opinions in the first place, insurers should either require them to undergo external audits or entrust the work to firms selected through an independent advisory selection committee." He added, "Transparency should also be secured by disclosing not only the hospitals with which the doctors are affiliated but also the doctors who provide medical opinions."
To improve the system's effectiveness, the internal-control guidelines must be placed under a higher-level law. Since their enactment in August 2021, they have remained voluntary self-regulatory guidelines. The Financial Services Commission and the Financial Supervisory Service are reviewing a plan to incorporate the guidelines into the Act on Corporate Governance of Financial Companies.
An insurance industry official said, "At present, there is no way to sanction violations of the rules, but bringing them within the framework of law would give them binding force." The official added, "The guidelines state that insurers should work to prevent medical opinions from being abused as a means of denying or reducing insurance payouts, but they contain no penalty provisions."
However, there are concerns that legislating the guidelines without revising them could expand insurers' authority through harmful provisions. Observers say the monitoring system for brokerage firms must be overhauled, while Article 10 also needs to be amended.
This is because the rules define the cases subject to medical opinions so broadly that insurance employees have considerable discretion to refer a case for a medical opinion even when the attending physician has provided an assessment. In other words, even if a doctor concludes that treatment is necessary, an insurer can exercise its discretion to seek another medical opinion.
More fundamentally, critics argue that the medical-opinion system is structured so that insurers pay to deny or reduce the insurance benefits of their own policyholders. They claim insurers pay brokerage firms and others for claims-adjuster labor, medical opinions, and legal consultations included in the net premium portion of insurance premiums, using them to deny or reduce payouts. Last year, medical opinions resulted in insurance payouts being denied or reduced in 28.3% of cases.
Min emphasized, "Insurers manage claims-adjustment expenses and use them for medical opinions or legal consultations intended to increase the victim's share of fault in liability cases." He added, "It would be reasonable to entrust these functions to an independent third-party institution."
An official from the General Insurance Association of Korea said, "Insurers have little incentive to manipulate medical opinions because they would risk fines or administrative penalties." The official added, "We will proceed with the legislation of the internal-control guidelines and other measures being pursued by the authorities once the details are finalized."
[email protected] Tae-il Kim Reporter