‘With 200 million won in debt, all-in on the kids?’ A couple in their 40s earning 9.1 million won a month with no spending cap [Money Planning Office]
- Input
- 2026-08-22 15:00:00
- Updated
- 2026-08-22 15:00:00
A couple’s monthly concern over 9.1 million won
A 46-year-old man identified as Kim Tae-hoon and his 44-year-old wife, Park Ji-eun, live in Gyeonggi Province and both work. Tae-hoon is a sales manager at a mid-sized company, while Ji-eun works in accounting at a small and medium-sized firm. Together, they earn 9.1 million won a month.They have two children, one in the first year of high school and the other in the first year of middle school. As the older child entered high school, academy fees and other costs rose sharply, and private education spending for the younger child has also begun in earnest. They need to prepare future college funds for their children, but Tae-hoon’s company is already talking about voluntary retirement for employees in their 50s. Seeing senior colleagues leave the company before retirement age has made them increasingly anxious.
The couple is unsure where to focus. Whenever they have extra money, they wonder whether it should go toward education costs or retirement savings.
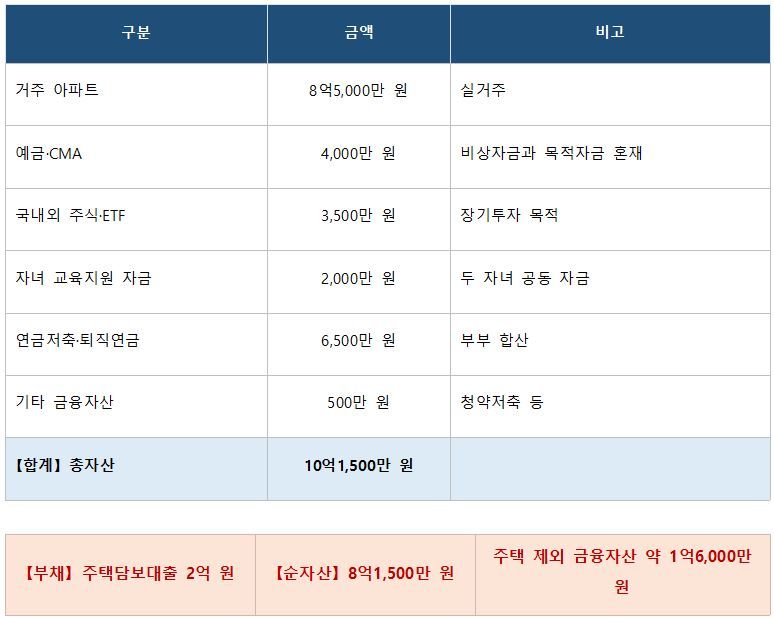
Their assets are not small. In total, they have 1.015 billion won. But if they exclude the apartment they live in, worth 850 million won, their financial assets come to 165 million won. Of that, 20 million won is set aside for children’s education, while 65 million won is in pension savings and retirement accounts. They also have 200 million won in mortgage debt.
Education spending should be limited to what they can responsibly cover
Financial planner Cho Hyung-geun, an AFPK-certified professional, advised that children’s education costs should be set not at the amount needed, but at the amount parents can responsibly afford.Ji-eun had been thinking about supporting not only college tuition, but also living expenses, language study abroad, certifications, exchange programs, and job preparation. The problem is that if there is no clear end point or limit, the support never stops. If the standard is simply "what is needed," support can continue even after marriage. Naturally, parents’ retirement planning gets pushed to the back burner.
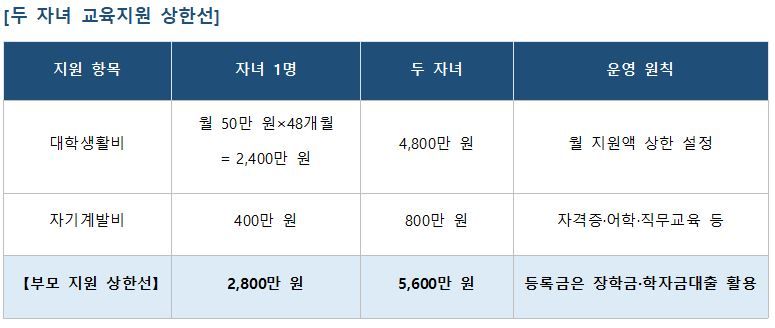
For that reason, the planner advised the couple not to set aside the full amount of college tuition in cash. Instead, they should use national and school scholarships first, and cover any remaining amount with student loans. As of the second semester of the 2026 academic year, the interest rate is about 1.7 percent. College living expenses can be set at 500,000 won a month, and self-development expenses at 4 million won per child. The key point is not the loan itself, but the need to set a cap on parental support.
They need to increase the share going to pensions and retirement accounts
The couple also needs to change how they manage money each month. Right now, they are putting 2.1 million won a month into savings and investments. But they are allocating 1.4 million won to children’s college living and self-development support, as well as additional mortgage repayment, while only 700,000 won goes to pension savings and retirement transition funds.The planner suggested cutting children’s education support from 800,000 won to 500,000 won and reducing the extra mortgage repayment from 600,000 won to 300,000 won. In return, he recommended increasing pension savings to 800,000 won and retirement transition funds to 400,000 won.
He said, "Children’s education support should not exceed 56 million won in total, and retirement preparation should never fall below 1.2 million won a month under any circumstances." He added, "That means setting a ceiling for the former and a floor for retirement savings."
There is also no need to focus solely on repaying debt. Reducing principal lowers interest, but if they use both emergency funds and retirement assets to pay off debt, they may end up short of financial assets to cover living expenses when they retire. For that reason, 35 million won out of their 40 million won in deposits and CMA accounts was set aside as emergency funds, while the rest was directed toward building retirement assets. Their mortgage repayment plan was also changed so that they pay an extra 300,000 won a month and add annual performance bonuses on top.
The planner said, "You do not have to stop retirement preparation just to pay off debt first." He added, "If interest rates rise or prepayment penalties disappear, you can increase the repayment share. But in principle, you should avoid paying off debt by liquidating pension accounts or long-term investment assets."
In the end, the greatest support a child can receive is for their parents’ retirement to remain intact. That is why education costs should be set at a level that does not damage parents’ post-retirement life. It may feel uncomfortable for now to have children use student loans, but if the goal is to prevent them from having to cover their parents’ living expenses later in life, then the parents’ retirement must be solid first.
Earning, spending, and saving money are repeated throughout life, but financial planning is always pushed aside. Yet money has an age too, and it does not wait. If you do not make choices each time, money is left unmanaged. If you do not set a direction, it slips away. That is why we need to design the flow of money across an entire lifetime.[Money Planning Office]supports life planning together with the Korea Financial Planner Association, the AFPK certification body.
[email protected] Kim Tae-il Reporter