"Hanwha Aerospace expected to earn 100 billion won, but made 300 billion more" ... "Doosan got a good deal on SK Siltron" [Stocktopia]
- Input
- 2026-08-03 11:02:12
- Updated
- 2026-08-03 11:02:12
[Financial News] Here is a roundup of major brokerage reports as of the morning of August 3.
Hanwha Aerospace has had its target price raised after analysts said its strong second-quarter earnings and robust order pipeline point to powerful order momentum in the second half.
EcoPro BM was seen as facing an unavoidable drop in third-quarter profit because of a gap in European customers, but analysts said the current share price is actually a buying opportunity based on its long-term growth potential. Doosan also drew praise for buying SK Siltron at a reasonable price, with expectations that the deal will lead to a re-rating of its corporate value.
Hanwha Aerospace's order pipeline alone is worth 50 trillion won, says Daol Investment & Securities.
◆Hanwha Aerospace (012450)— Daol Investment & Securities / Analyst Choi Gwang-sik- Target price: 2.14 million won (up 4.9% from 2.04 million won) | Previous close: 917,000 won
- Investment rating: Buy (maintained)
Daol Investment & Securities raised its target price for Hanwha Aerospace to 2.14 million won, saying the company delivered second-quarter results that far exceeded market expectations.
Choi Gwang-sik, an analyst at Daol Investment & Securities, said, "Operating profit in the second quarter came to 1.3655 trillion won, delivering a surprise of 1.37 trillion won and far exceeding the 1 trillion won consensus." He added, "Subsidiaries such as Hanwha Ocean and Hanwha Systems also beat expectations, and the land defense business was better than expected despite weak export data." In other words, the shipbuilding and defense affiliates both performed strongly, allowing the company to earn more than 300 billion won above what the market had anticipated.
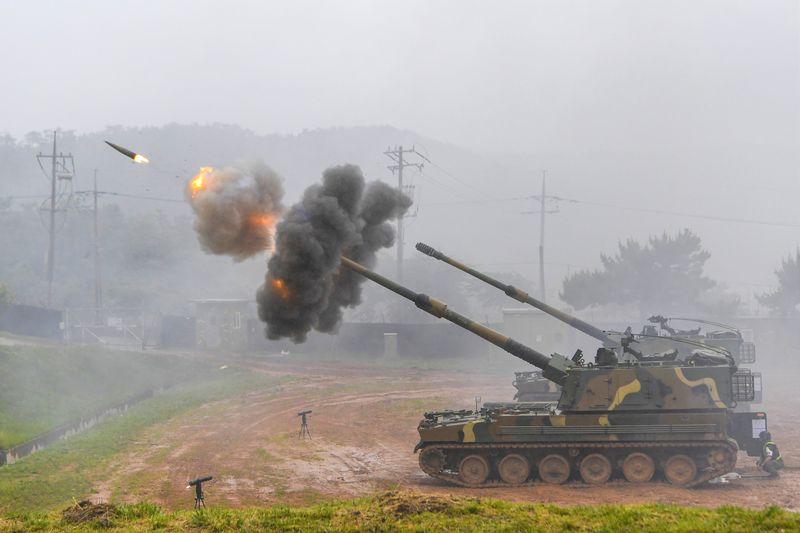
What stands out is that land defense sales increased even though export statistics barely captured the domestically produced K9 Thunder. Choi said, "There were many deliveries of K9-related parts, and ammunition shipments were steady," adding, "It will likely become even harder to estimate the company's exports going forward." The analysis suggests that even without deliveries of complete weapons systems, steady parts and ammunition shipments are supporting earnings, confirming export strength that does not show up clearly in the statistics.
In the second half, sales from the second K9 contract with Poland are expected to accelerate, while shipments to Egypt and Australia are also continuing steadily. As a result, stronger earnings are expected in the second half, just as last year.
Daol Investment & Securities estimated that the order pipeline yet to be decided, including Spain's self-propelled howitzer project, U.S. self-propelled howitzer modernization, the third K9 batch for Poland, and a Saudi Arabia National Guard project, amounts to 50 trillion won.
EcoPro BM sees lower third-quarter profit due to the European gap, says Hana Securities.
◆EcoPro BM (247540)— Hana Securities / Analyst Kim Hyun-soo- Target price: 154,000 won (down 40.1% from 257,000 won) | Previous close: 103,500 won
- Investment rating: Buy (maintained)
Hana Securities sharply cut its target price for EcoPro BM to 154,000 won, saying a decline in third-quarter profit is unavoidable. Even so, it maintained its Buy rating, arguing that too much risk is already reflected in the current share price.
Kim Hyun-soo, an analyst at Hana Securities, explained, "A gap in new projects for major customers in the European market is expected to continue until the first half of next year." He added, "This makes weaker cathode material shipments unavoidable."
The company is also expected to be hit by a major customer's split of supply channels in the North American Energy Storage System (ESS) market. As a result, operating profit in the third quarter is estimated to fall 74% from a year earlier.
Still, Kim said, "Given that the battery sector has typically priced in earnings two to three years ahead, the current price is a buying opportunity." He argued that once the order volumes scheduled from 2028 are reflected, annual earnings will rise sharply, so investors should focus on the growth beyond the near-term slowdown.※ Cathode materialThis is a core material that forms the positive electrode in a battery. It stores lithium ions, which act as the medium for electricity, and then releases them when needed. The battery's capacity, output, and safety vary depending on the ratio of metals such as nickel, cobalt, manganese, and aluminum mixed with lithium. It accounts for the largest share of battery costs, and EcoPro BM mainly produces NCA cathode material, which combines nickel, cobalt, and aluminum.※ Energy Storage System (ESS)This is a device that stores electricity and uses it when needed. It is widely used to store intermittent power from solar and wind sources, and as backup power for data centers that consume large amounts of electricity.
Doosan Group vertically integrates semiconductors all the way to wafers, says Kiwoom Securities.
◆Doosan Group (000150)— Kiwoom Securities / Analyst Kwon Min-kyu- Target price: 2.2 million won (maintained) | Previous close: 1.17 million won
- Investment rating: Buy (maintained)
Kiwoom Securities praised Doosan Group's decision to acquire a 70.61% stake in SK Siltron for 230 billion won, calling it a deal that bought only the best assets at a reasonable price. It maintained its target price of 2.2 million won and its Buy rating.
On a 100% equity basis, the implied enterprise value of the acquisition is about 8.1 times SK Siltron's annual cash earnings, which is lower than the 10.2 times average for global wafer rivals such as Shin-Etsu and SUMCO Corporation.
Kwon Min-kyu, an analyst at Kiwoom Securities, said, "The base equity value was set at a level lower than the amount previously discussed in the market, which eased concerns about the cash burden." He added, "This is a sound acquisition focused on core assets, and because Doosan Group bought well at a low price, it is now time for the company's value to be re-rated."
The deal structure also favors Doosan Group. From 2027 to 2034, the company will pay additional money to SK only if SK Siltron's results exceed a set benchmark, under an earn-out clause. That means it pays more only when performance improves, while avoiding downside risk if results weaken. The loss-making silicon carbide (SiC) wafer business will be liquidated and carved out, leaving only the core silicon wafer business with an operating margin of around 20%.※ Earn-outThis is a deal structure used when buying or selling a company, in which the full price is not set upfront. If the acquired company exceeds agreed performance targets after the deal, the buyer pays the seller additional money later. The buyer can reduce the initial cash burden and avoid downside risk, while the seller can share in the upside if the business performs well.※ Silicon waferThis refers to a round disk made by slicing thin layers from an "ingot," a cylindrical block created by melting silicon extracted from sand. Microcircuits are etched onto the wafer and then cut into semiconductor chips used in smartphones, computers, and other devices.
[Stocktopia]is an AI-based stock report briefing service that compiles and delivers reports from major domestic securities firms. If you would like to keep receiving [Stocktopia], please subscribe to the reporter's page.
[email protected] Sung Min-seo Reporter