"SK hynix Seen Rising to 4.7 Million Won" Korea Investment Raises Target Again, BNK Cuts It Again to 1.48 Million Won
- Input
- 2026-07-30 09:07:04
- Updated
- 2026-07-30 09:07:04
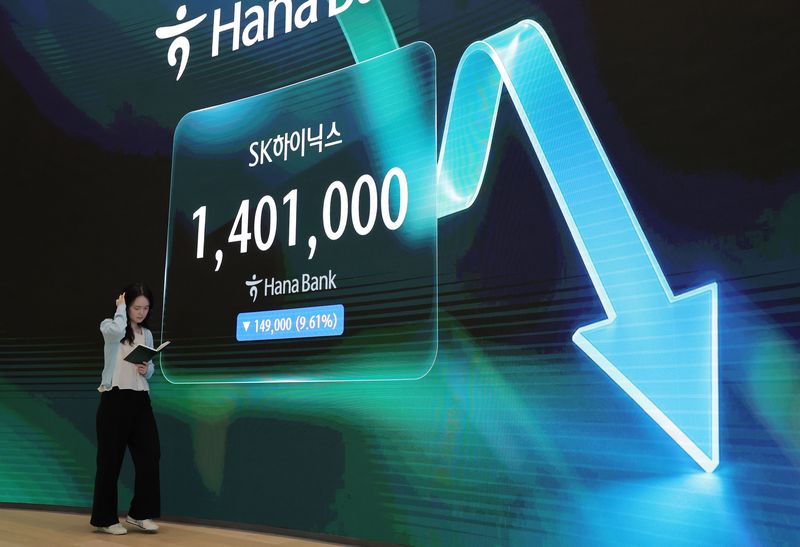
[Financial News] SK hynix has fallen sharply for a second straight day, and market views on the reason are sharply divided. Some brokerages have slashed their target prices, while others have raised them instead.
Korea Investment says third-quarter DRAM prices will rise more than 20%
According to The Korea Economic Daily on the 30th, Korea Investment & Securities raised its target price for SK hynix from 3.8 million won to 4.7 million won and maintained its buy rating. The firm said DRAM prices will keep rising in the third quarter of this year and drive earnings.
Chae Min-suk, an analyst at Korea Investment & Securities, said second-quarter operating profit fell short of market expectations because DRAM price gains were weaker than expected. She added, however, that this was only a temporary effect caused by the postponement of high-value-added product shipments to the second half, not a sign of weaker demand, and said it would instead support earnings improvement in the third quarter.
She forecast that DRAM prices in the third quarter will rise 20%, above her previous estimate of 10% quarter on quarter.
As a result, Korea Investment & Securities raised its operating profit forecasts for SK hynix by 10% and 11% for this year and next year, respectively, to 27 trillion won and 41.8 trillion won.
The firm said the combination of high average selling prices based on long-term supply agreements (LTA) of up to five years and full-scale mass production of sixth-generation high-bandwidth memory (HBM4), which will begin in the third quarter, will further boost HBM prices.
Chae said, "We believe the recent stock price correction reflects growing market skepticism about the sustainability of AI investment rather than changes in fundamentals." She added, "Even though memory prices have risen fourfold from a year earlier, hyperscalers are continuing to invest in AI infrastructure."
She continued, "As customers ask for shipments to be brought forward, production volumes are being shipped immediately, leaving both memory suppliers and customers without sufficient safety stock. The supply shortage will deepen further in the second half of this year and into next year."
She also said, "The market is pricing in doubt, but solid fundamentals are being proven through earnings." She emphasized that "now is the time to focus on the direction of corporate value and profits rather than short-term stock price moves."
Mirae Asset says the current drop is excessive
By contrast, Mirae Asset Securities and BNK Investment & Securities cut their target prices for SK hynix on the 29th to 2.8 million won and 1.48 million won, respectively, from 4.2 million won and 1.85 million won.
Kim Young-geon, an analyst at Mirae Asset Securities, told Yonhap News Agency that the reason for the lower target price was that the stock had already adjusted on expectations of lower NAND flash memory contract prices, only to be followed immediately by concerns over China's localization of lithography machines. He added that, in the latter case, the impact on earnings estimates through 2028 would likely be limited, so the firm only lowered its target multiple.
Kim said, "Given its earnings power and financial stability, the recent stock decline is largely excessive." He added, "With limited changes in the industry and fundamentals, the stock is falling mainly on valuation concerns."
Meanwhile, SK hynix plunged 9.61% on the 29th, falling into the 1.4 million won range and extending its sharp decline for a second day. In just two trading days, the stock dropped 22.85%.
SK hynix's closing price was down 53% from its intraday peak of 2.987 million won on the 25th of last month, and its market capitalization has shrunk by more than 8.1 trillion won.
[email protected] Kim Su-yeon Reporter